Kenya is connecting mobile money, e-commerce and finance to chase global digital trade

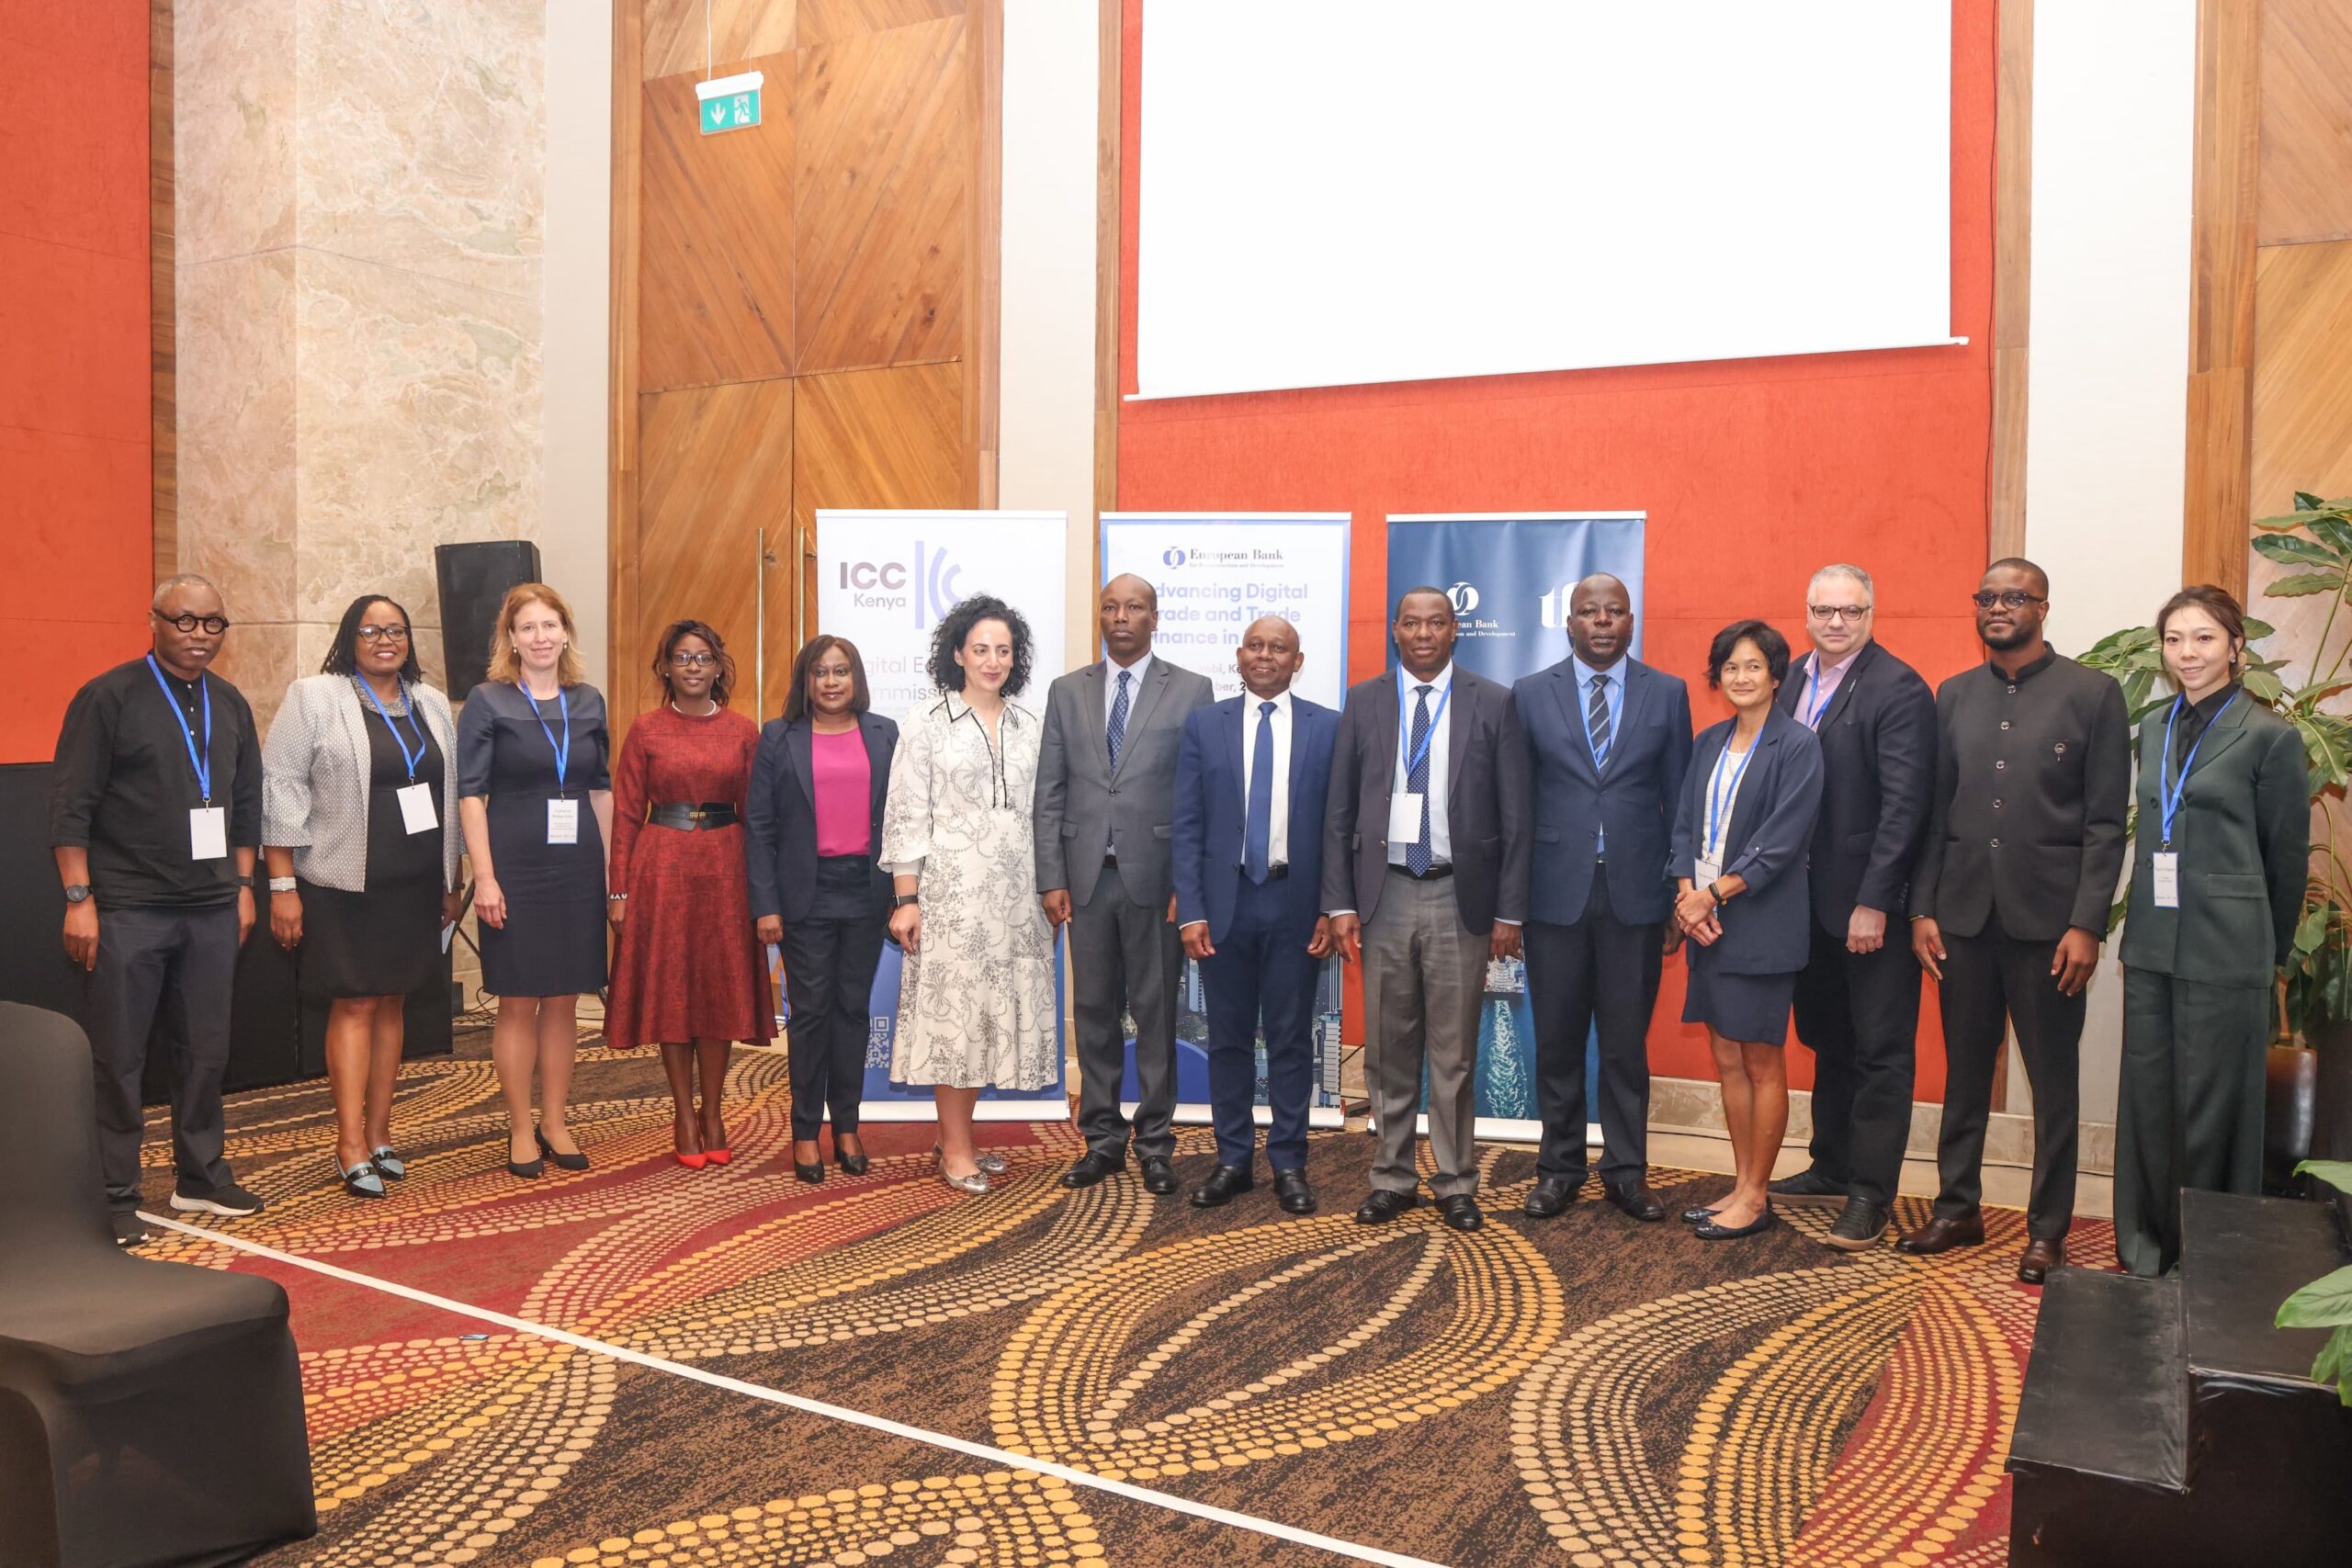
Kenya’s digital trade is entering a more consequential stage as the government seeks a larger share of international commerce conducted through digital platforms, payments and cross-border online transactions.
Investment, Trade and Industry Cabinet Secretary Lee Kinyanjui said Kenya can become a leading African digital trade hub, but identified infrastructure, logistics, financing and regulation as barriers that need to be addressed. The comments came at a high-level workshop on advancing digital trade in Kenya organised by the European Bank for Reconstruction and Development.
The government estimates that the digital economy could contribute Sh662 billion to Kenya’s GDP by 2028, while Kinyanjui cited a global digital trade market worth $8.75 trillion in 2025, equivalent to about 25 per cent of global trade in goods and services. Those figures put a large number around an opportunity that Kenya has already been building toward through mobile money, broadband, e-commerce, digital banking and online business services. The more important question now is whether those systems can work together well enough for Kenyan businesses to sell, receive payments, obtain financing and deliver products across borders at competitive cost.
Kenya already has much of the digital trade foundation
Kenya’s starting position is stronger than the headline about chasing a share of global digital trade might suggest. The country’s mobile market had almost 88 million SIM subscriptions by June 2026, alongside 52.26 million smartphones and nearly 55 million mobile broadband subscriptions. That combination gives digital businesses a large addressable base of consumers and merchants, although SIM subscriptions and smartphone connections should not be interpreted as unique users.
The e-commerce market is also developing beyond a small collection of online retailers. Kenya’s e-commerce market could grow from about Sh336.7 billion to roughly Sh496 billion by 2029, with internet access, mobile payments and online shopping supporting the expansion. The same market, however, faces practical constraints around taxation, electronic invoicing, delivery networks, consumer protection and cross-border rules.
That distinction is important because digital trade is much broader than putting products on a website. A Kenyan business selling through WhatsApp, a marketplace or its own online store still needs a payment rail, customer identity and fraud controls, working capital, inventory, delivery, returns and a way to handle disputes. If the customer is outside Kenya, the transaction also brings foreign exchange, customs, tax and cross-border settlement into the picture.
Kenya’s payments ecosystem is already adapting to that wider definition of commerce. Safaricom and Pesapal introduced M-Pesa tap-to-pay and dynamic QR payments at Pesapal point-of-sale terminals in October, with Scan-to-Pay already available at more than 60,000 merchant outlets and Safaricom targeting 500,000 outlets within 12 months. The development is focused on physical retail, but it illustrates a broader trend in which mobile money is becoming part of a wider payments infrastructure rather than remaining confined to person-to-person transfers.
Mobile money is moving closer to global commerce
The clearest example of this expansion is the competition between Kenya’s two largest mobile operators. Airtel Money is preparing to introduce a Mastercard-powered virtual card in Kenya, allowing customers to use their mobile-money balance for international online purchases and digital services. The service is already available in several other African markets, with more than 875,000 cards issued across those markets since its 2025 launch.
Safaricom is pursuing a similar connection between M-Pesa and international commerce through M-Pesa GlobalPay and other services. Its global payments revenue rose 22.3 per cent to KSh4.8 billion in the financial year ended March 2026, although that figure includes international transfers, virtual cards and Google Play Store payments rather than virtual-card activity alone. Total M-Pesa revenue reached KSh182.7 billion during the same period.
This matters for digital trade because the payment interface is becoming less of a barrier between Kenyan consumers and overseas merchants. A consumer who can pay an international digital service directly from a mobile-money balance is participating in cross-border digital commerce without needing the traditional sequence of a bank account, physical card and separate foreign-currency payment process.
The same infrastructure can work in the other direction. Kenyan merchants selling goods or digital services abroad need reliable ways to receive money, manage foreign currency and reconcile transactions with their business records. That is where payment connectivity begins to intersect with trade finance, banking and regional settlement.
M-Pesa’s own continental footprint illustrates the scale of the underlying platform. M-Pesa Africa reported its first operating profit in 2026, with revenue rising 20.6 per cent to Sh8.08 billion and the platform reaching 60 million users across Africa. Its ecosystem now spans payments, merchant services, credit, savings and other financial products, giving a Kenyan-origin payment platform a much wider regional role.
Cross-border finance remains a major constraint
Payments alone cannot turn digital demand into trade. A merchant may find customers through an online platform and receive an electronic order, but still need money to purchase stock, pay suppliers, import equipment, cover shipping and manage the period between dispatch and settlement.
A $10 million trade-finance facility agreed between the African Development Bank and Family Bank this week illustrates the size of that problem. The facility is designed to expand access to foreign currency and financing for Kenyan businesses, including SMEs and companies operating in manufacturing, agriculture, healthcare, renewable energy and general commerce. The African Development Bank estimates Africa’s trade-finance gap at more than $74 billion.
For smaller businesses, this can determine whether access to an international customer becomes a genuine export opportunity or simply an order that is too expensive to fulfil. Family Bank says MSMEs account for more than 80 per cent of its customer base, while the new facility is intended to support imports, productive sectors and intra-African trade.
Digital records could also make financing more useful to smaller enterprises. Sales, payment and transaction histories can potentially give lenders additional information about business performance and cash flow, which could help them assess enterprises that lack conventional financial histories. But that benefit depends on lenders having appropriate data access, sound credit models and safeguards around customer information.
The financial layer is therefore becoming part of the digital-trade infrastructure itself. Absa’s new digital platform, for example, combines payments, savings, credit, investments and business-finance tools, while other Kenyan banks and fintechs are pursuing similar efforts to keep more business activity within digital channels. The competition is gradually moving around the entire financial relationship rather than one isolated banking product.
Logistics and trust will determine how far digital trade goes
There is a physical limit to digital commerce: products still have to move.
Kinyanjui highlighted customs, logistics, transport and trade facilitation because an online transaction does not eliminate the physical process required to deliver goods across a border. A Kenyan seller can accept an order from Uganda, Rwanda, Nigeria or a customer elsewhere in Africa within minutes, but the transaction can still encounter delays at customs, high shipping costs, fragmented standards, inefficient returns processes or limited delivery networks.
Recent growth in digital parcel delivery in Kenya offers another piece of the same picture. Digital commerce depends on delivery infrastructure that can handle increasing transaction volumes reliably, including outside Nairobi. The growth of online trade therefore creates pressure on courier networks, warehousing, fulfilment systems and the broader transport infrastructure that sits behind the screen.
Trust is equally important. Kenyan consumers are using mobile phones as a major gateway to online commerce, with 71.3 per cent of respondents in the Communications Authority’s 2024/25 Consumer Satisfaction Survey saying they use phones to access e-commerce platforms. As transactions move through social platforms, messaging applications, mobile-money wallets and card interfaces, consumers need confidence that sellers are genuine, payment requests are legitimate and disputes can be resolved.
That makes cybersecurity and consumer protection economic infrastructure rather than compliance issues sitting on the edge of the market. Fraud can directly reduce willingness to transact online, while weak data protection can undermine confidence in platforms handling payment, identity and purchasing information.
Regulation has to keep pace with connected payment systems
Kenya’s regulatory environment is also being forced to account for a payments market where banks, mobile-money providers, fintechs, SACCOs and payment processors increasingly connect to one another.
The proposed National Payment System Bill is one example. The proposed framework would give the Central Bank of Kenya broader powers over payment service providers and payment system operators, while covering areas including interoperability, open finance, outsourcing, system audits, clearing and settlement, cross-border payments and payment transparency.
That matters for digital trade because a transaction can now cross several technical and institutional boundaries before a merchant receives its money. A customer may discover a product on a social platform, communicate with a seller through messaging, pay through mobile money or a card, rely on a bank or fintech for financing and use a separate logistics provider for delivery. A regulatory failure or operational weakness in any one layer can affect the wider transaction.
The same principle applies to emerging payment technologies. Kenya’s virtual-asset regulations and its broader debate around interoperability and regional settlement are bringing mobile money, digital assets, payment providers and cross-border transactions into closer proximity. The existence of a regulatory framework, however, does not automatically mean that new rails will achieve broad merchant adoption or eliminate the cost and friction associated with cross-border payments.
Regional integration will require practical implementation as much as policy alignment. Kenya’s participation in EAC digital-trade initiatives, the AfCFTA Digital Trade Protocol and the WTO Trade Facilitation Agreement gives businesses a framework for reaching wider markets, while AfCFTA potentially connects Kenyan companies to a continental market of more than 1.4 billion people.
Kenya’s opportunity extends beyond online shopping
The strongest case for Kenya’s digital-trade strategy is therefore not simply that more consumers will buy products online. The larger opportunity is to connect Kenyan companies to regional and international customers while allowing payments, finance, logistics and business records to operate through digital systems.
That could benefit exporters, manufacturers, professional-service firms, software companies, creators, logistics businesses and small merchants alongside conventional e-commerce retailers. A Kenyan software developer does not face the same logistics problem as a clothing seller, but both need reliable cross-border payments, predictable regulation and access to customers outside the domestic market.
The government’s own priorities point in that direction. Kinyanjui said investment would continue in digital infrastructure, including efforts to narrow the urban-rural connectivity gap, while digital skills among MSMEs, women and young people would receive greater attention. Those measures matter because a digital market cannot be considered broad-based if the smallest businesses lack the connectivity, skills or financing required to participate.
Kenya already has several of the components needed for that market: a large smartphone base, widespread mobile money, established digital payments, a growing e-commerce sector and financial institutions building digital services around businesses and consumers. The challenge is connecting those components to the less visible infrastructure of trade, including foreign exchange, working capital, customs, delivery, consumer protection and cross-border settlement.
That is where the government’s ambition to capture a larger share of global digital trade will be judged. The payment can move in seconds, and an online order can reach a Kenyan seller instantly, but the economic value of the transaction depends on everything that happens around it. If Kenya can reduce the friction between discovery, payment, financing and delivery, its existing digital infrastructure can support a much larger role in regional and global commerce.
Real ESG impact doesn’t happen in panels alone, it happens in the rooms where financiers, operators, and policymakers actually align. Our GreenShift Forum 2026 cuts the noise, bringing together the people rewiring Africa’s sustainability and energy frameworks for one focused day in Nairobi. Secure your seat.
Go to TECHTRENDSKE.co.ke for more tech and business news from the African continent and across the world.
Follow us on WhatsApp, Telegram, Twitter, and Facebook, or subscribe to our weekly newsletter to ensure you don’t miss out on any future updates. Send tips to info@techtrendsmedia.co.ke