Eric Muriuki joins Absa as the bank assembles a new Pan-African digital leadership team

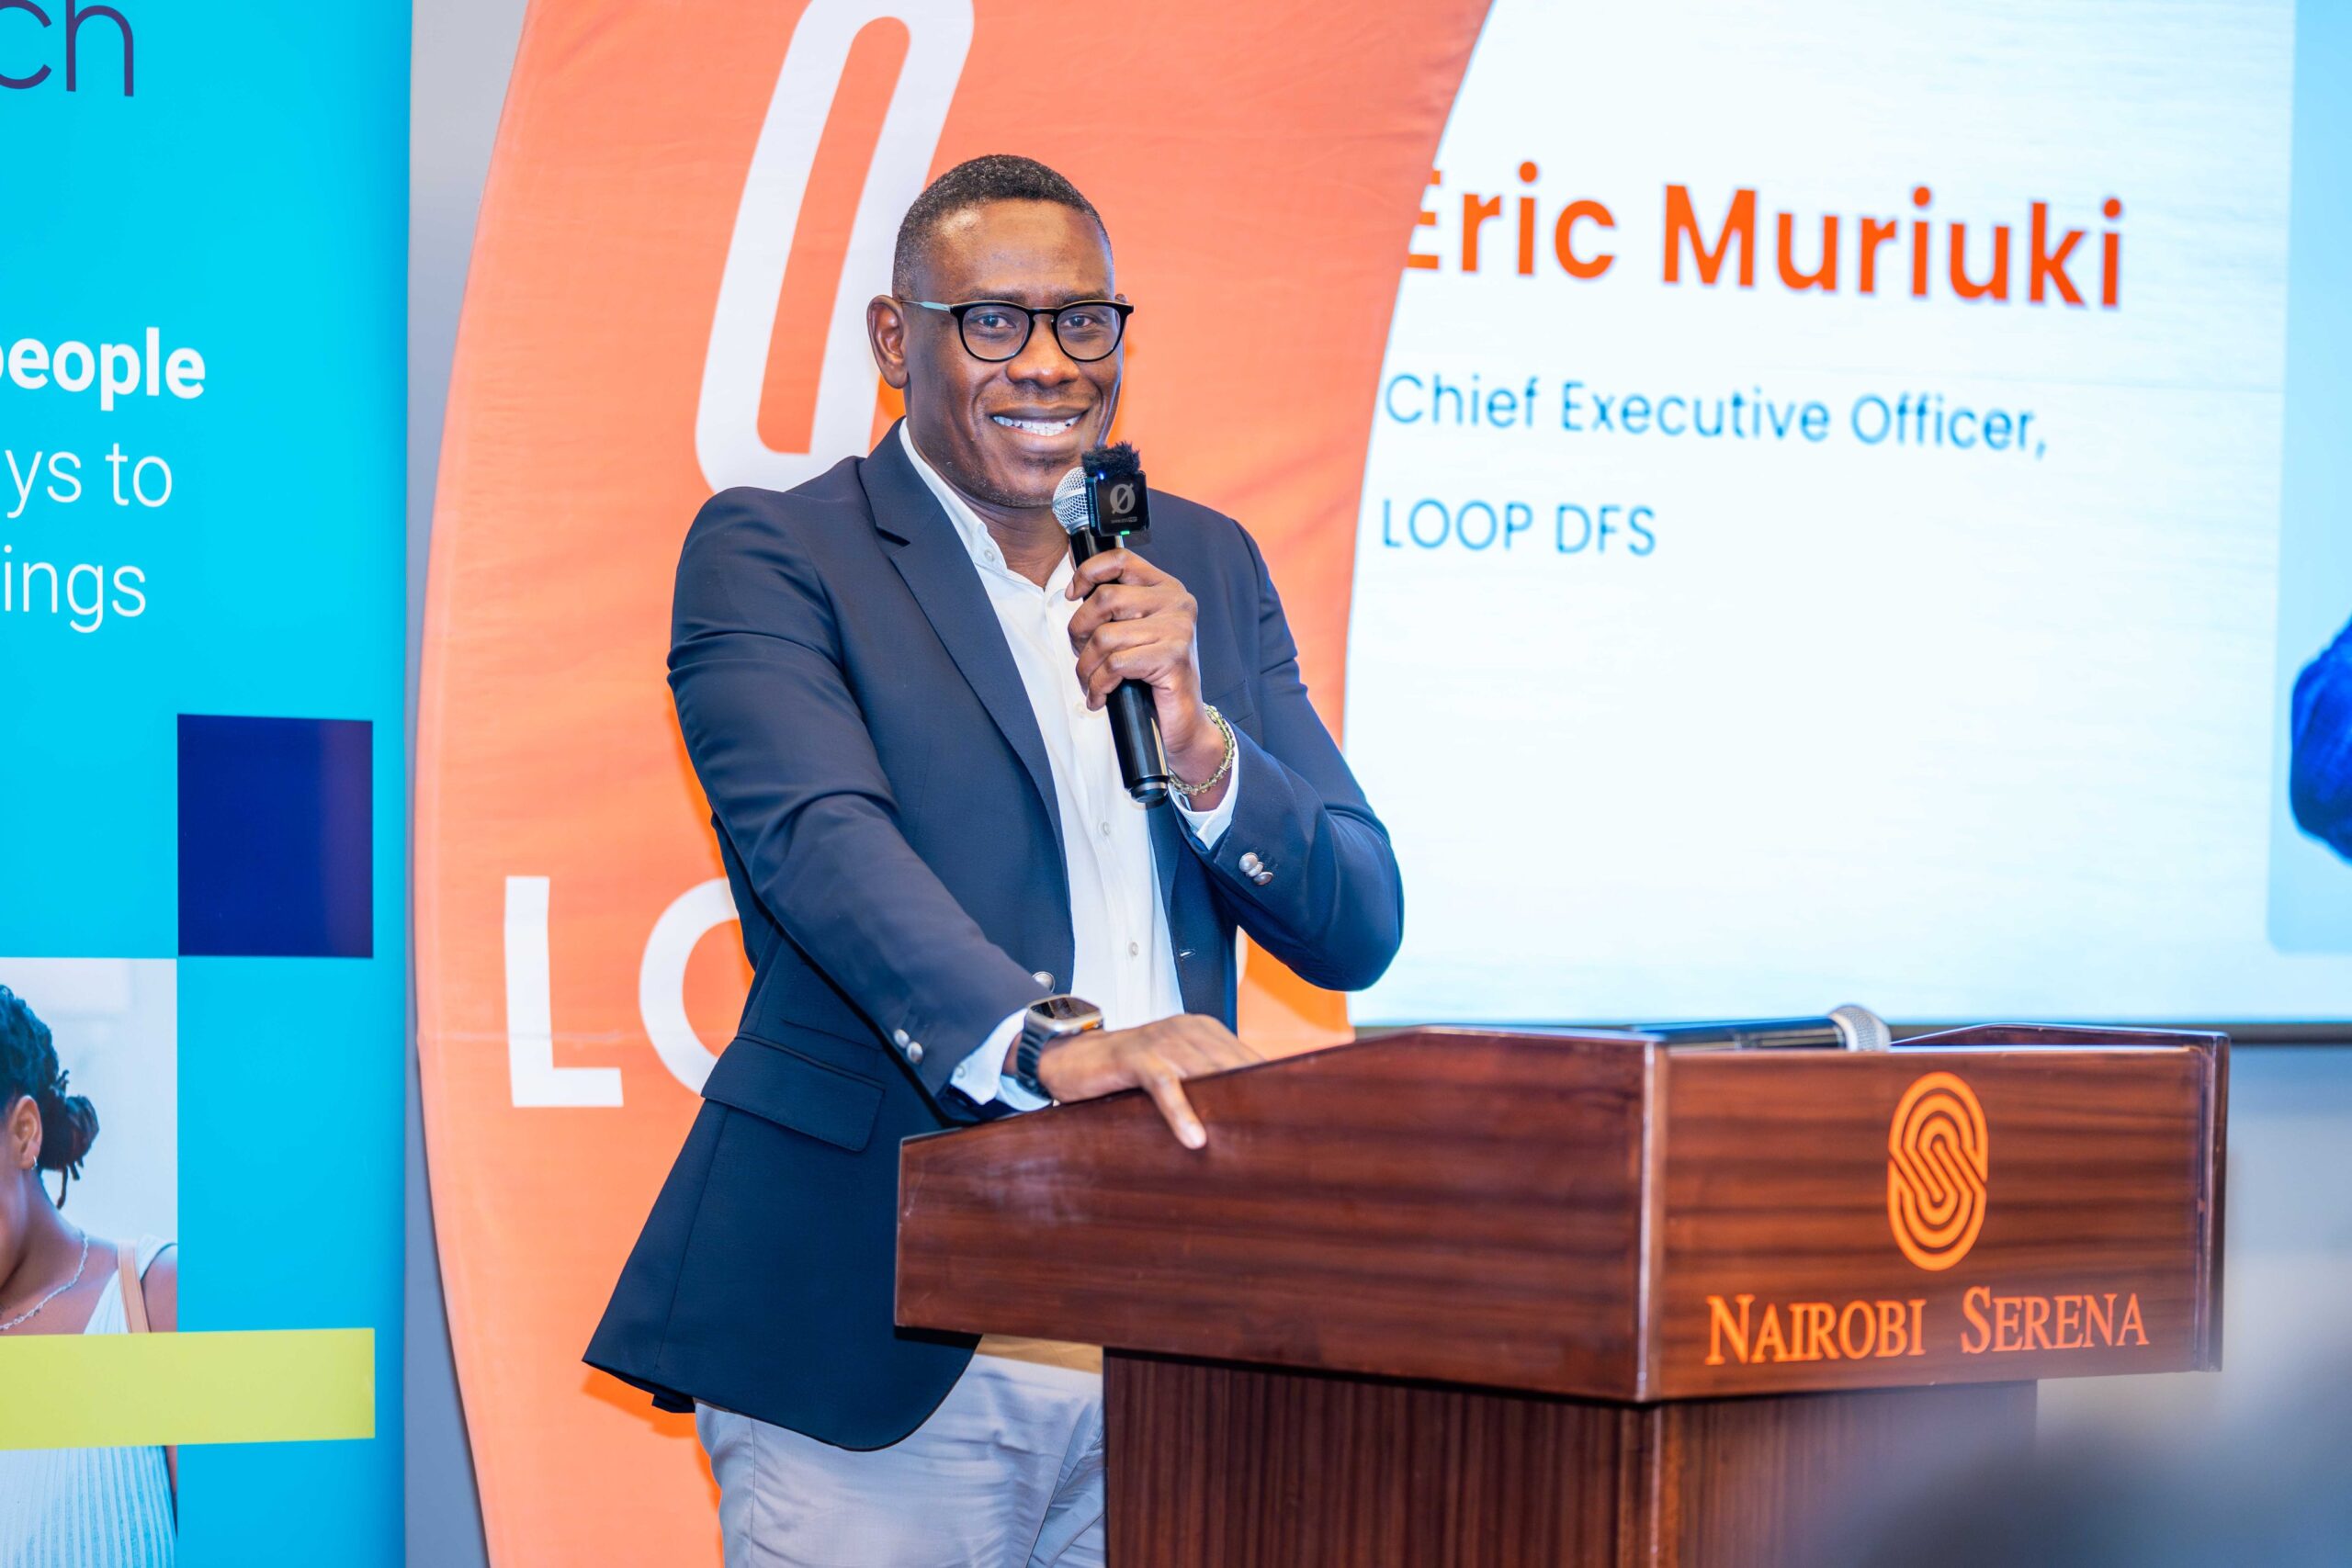
Eric Muriuki joins Absa Group at a point when the banking industry is becoming more focused on digital platforms, everyday payments and financial services that sit outside the traditional bank account.
The former NCBA executive is taking up the role of Managing Executive for Pan-African Growth Strategy, Platforms and Digital Ventures, adding nearly two decades of Kenyan banking and digital-finance experience to an Absa leadership team that has been substantially reshaped in 2026.
Muriuki’s appointment is significant because it brings together two developments that have been unfolding separately. Absa has been rebuilding its senior leadership around its refocused Pan-African strategy, while Kenya’s major banks are creating digital platforms designed to capture more of the transactions, data and customer relationships that have historically moved between banks, mobile-money operators and fintechs. His experience running LOOP DFS places him directly within that intersection.
Absa’s leadership reset goes beyond one appointment
Absa’s executive changes began well before Muriuki’s arrival. Zaid Moola became Chief Executive of Corporate and Investment Banking on January 1, 2026, bringing more than two decades of corporate and investment banking experience across Africa. In April, former M-PESA Africa CEO Sitoyo Lopokoiyit became Chief Executive of Personal and Private Banking, bringing extensive experience in mobile money, fintech and digital financial services.
The group subsequently appointed Leon Barnard as Chief Executive of Business Banking across Pan Africa, effective June 1. Absa described Business Banking as a core engine of growth and highlighted Barnard’s experience spanning customer strategy, regional operations, payments and digital strategy. In Kenya, Abdi Mohamed’s departure to lead I&M Bank was followed by Yusuf Omari’s appointment as Absa Bank Kenya’s Managing Director and CEO after serving as interim chief.
Taken together, the appointments point to a leadership structure built around distinct customer franchises, regional operations and technology-enabled financial services. Muriuki’s portfolio adds another layer: the group-level development of platforms and digital ventures, alongside the broader Pan-African growth agenda.
That matters because Absa’s challenge is no longer confined to expanding a conventional banking operation from one country into another. The group has to determine which digital capabilities can be reused across markets, which need local adaptation and how technology can help it acquire and retain customers beyond established banking channels.
Muriuki brings the LOOP experience to Absa
Muriuki spent most of his banking career at CBA and, following its 2019 merger with NIC, NCBA. He joined CBA in July 2007 and went on to hold roles spanning enterprise transformation and new business ventures before becoming Group Director of Digital Business and CEO of LOOP DFS.
His career is particularly relevant to Absa because LOOP itself illustrates how a bank’s digital strategy can evolve. What began as an urban-focused digital banking proposition developed into a broader financial-services platform, with products and infrastructure supporting lending, device financing, Buy Now Pay Later services and embedded credit.
Muriuki has also been associated with the development of financial products involving CBA and Safaricom, including M-Shwari, while his career has included work around the banking architecture supporting mobile-money services.
That combination of banking infrastructure, digital products, lending and platform development is closely aligned with where Absa is directing its technology strategy.
Why digital platforms matter to African banks
Kenya’s banking market is showing why these capabilities matter. More than 90% of retail transactions at major Kenyan banks now take place outside branches. The physical branch remains relevant, but it is no longer the primary interface through which many customers interact with financial institutions.
The strategic problem for banks is that an account can remain with a bank while the customer’s everyday financial activity happens elsewhere. A salary or business payment may enter a bank account before being transferred to M-PESA, Airtel Money or another wallet for spending, transfers and merchant payments.
That movement affects more than transaction revenue. Everyday payments generate behavioural information that can help financial institutions understand how customers earn, spend and manage liquidity. Those patterns can feed credit decisions, customer segmentation and product design, particularly for consumers and small businesses that may not have conventional collateral.
This is why the competition between banks, mobile-money operators and fintechs increasingly involves the interface through which customers manage money. Whoever owns more of the daily transaction relationship has more opportunities to provide payments, savings, credit, insurance and other services around it.
Absa Next puts the strategy into practice
Absa’s response in Kenya is already visible through Absa Next, a cloud-based digital platform launched in September that is available to both Absa customers and people who do not bank with the institution.
The platform combines banking, savings, investments, payments and lending, while allowing users to connect external financial accounts. It offers instant loans ranging from KSh500 to KSh1 million using alternative credit assessment and broader behavioural information. Absa has also positioned the platform as a technology model that could have relevance beyond Kenya.
The distinction between Absa Next and a conventional mobile-banking application is important. The bank is running it alongside its existing banking application and making it available to non-customers, giving the platform a role in customer acquisition as well as servicing people who already hold Absa accounts.
That approach gives Muriuki’s new portfolio a practical reference point. Absa is already building a digital proposition that extends beyond the boundaries of its traditional customer base. A group executive responsible for platforms and digital ventures can potentially connect that work with the bank’s wider operations across Africa.
Whether Absa can actually achieve that at scale will depend on how much of the platform can be standardised across markets. Payments infrastructure, regulation, credit data, mobile-money penetration and customer behaviour vary considerably between African countries.
Equity and NCBA show where the market is heading
Absa is also operating in a market where other large banking groups are pursuing similar models.
Equity Group has launched EMMA through its fintech subsidiary Finserve Africa. The wallet is available through an Android application, USSD and the Equitel SIM toolkit, with services covering payments, savings, loans and bills. It is also designed to interact with external financial ecosystems, including M-PESA, Airtel Money and commercial bank accounts.
The strategic logic is similar to Absa Next. Equity already has a large banking operation, agency network, Equitel and established payment infrastructure. EMMA gives the group another interface through which it can compete for everyday transactions while gathering information about how customers use financial services.
NCBA provides the third example. LOOP, which Muriuki led, has evolved beyond its original digital-bank proposition toward embedded finance and platform services. That progression reflects a wider change in how banks view digital businesses: the objective is no longer simply to reproduce traditional banking products inside an app, but to place financial services closer to where customers conduct commerce.
The three cases are different in structure, but they point toward the same competitive problem. Banks want to remain relevant when customers increasingly interact with money through wallets, merchant platforms, apps, APIs and other digital interfaces rather than through a bank branch or conventional account screen.
Muriuki’s mandate extends beyond Kenya
That makes the Pan-African element of Muriuki’s appointment particularly important.
Absa operates across multiple African markets, each with different financial ecosystems. A platform that works in Kenya cannot simply be copied into another market without considering local payment rails, mobile-money operators, regulations, consumer behaviour and existing financial institutions.
The opportunity is to build technology and operating capabilities that can be reused while allowing individual markets to retain the products and partnerships that customers actually use. Absa’s interest in Tanzania is instructive. Sitoyo has highlighted the country’s mobile-money ecosystem and the wider opportunity to improve cross-border financial connectivity, including the high cost of moving money between African markets.
This also fits Absa’s broader approach to fintech partnerships. The group has been pursuing models that put financial services inside platforms customers already use instead of relying exclusively on a standalone banking application.
Muriuki therefore arrives with experience that spans the development of digital banking propositions, lending and financial-services platforms in one of Africa’s most mature digital-finance markets. His new role gives that experience a much wider geographic remit.
The bigger question for Absa
The appointment gives Absa another senior executive with direct experience of the competition between banks, mobile money and fintech platforms. It also completes a broader picture of the group’s 2026 leadership changes, which have brought in expertise across mobile money, corporate banking, business banking, digital services and regional operations.
But the personnel changes alone will not determine whether the strategy works. Absa still has to convert those capabilities into platforms that can attract customers, generate sustainable revenue and operate across markets with very different financial infrastructures.
Kenya provides a useful proving ground because customers are already accustomed to moving between bank accounts, mobile wallets, fintech applications and merchant platforms. Equity’s EMMA, Absa Next and the evolution of NCBA’s LOOP show that the major banks recognise the same competitive reality from different positions.
Muriuki’s move places him at the centre of Absa’s response. The question for the group now is whether it can turn a collection of strong digital capabilities and newly appointed executives into a coherent Pan-African platform strategy that works beyond the Kenyan market.
Real ESG impact doesn’t happen in panels alone, it happens in the rooms where financiers, operators, and policymakers actually align. Our GreenShift Forum 2026 cuts the noise, bringing together the people rewiring Africa’s sustainability and energy frameworks for one focused day in Nairobi. Secure your seat.
Go to TECHTRENDSKE.co.ke for more tech and business news from the African continent and across the world.
Follow us on WhatsApp, Telegram, Twitter, and Facebook, or subscribe to our weekly newsletter to ensure you don’t miss out on any future updates. Send tips to info@techtrendsmedia.co.ke