Absa Next: How Absa is rethinking digital banking and the customer relationship

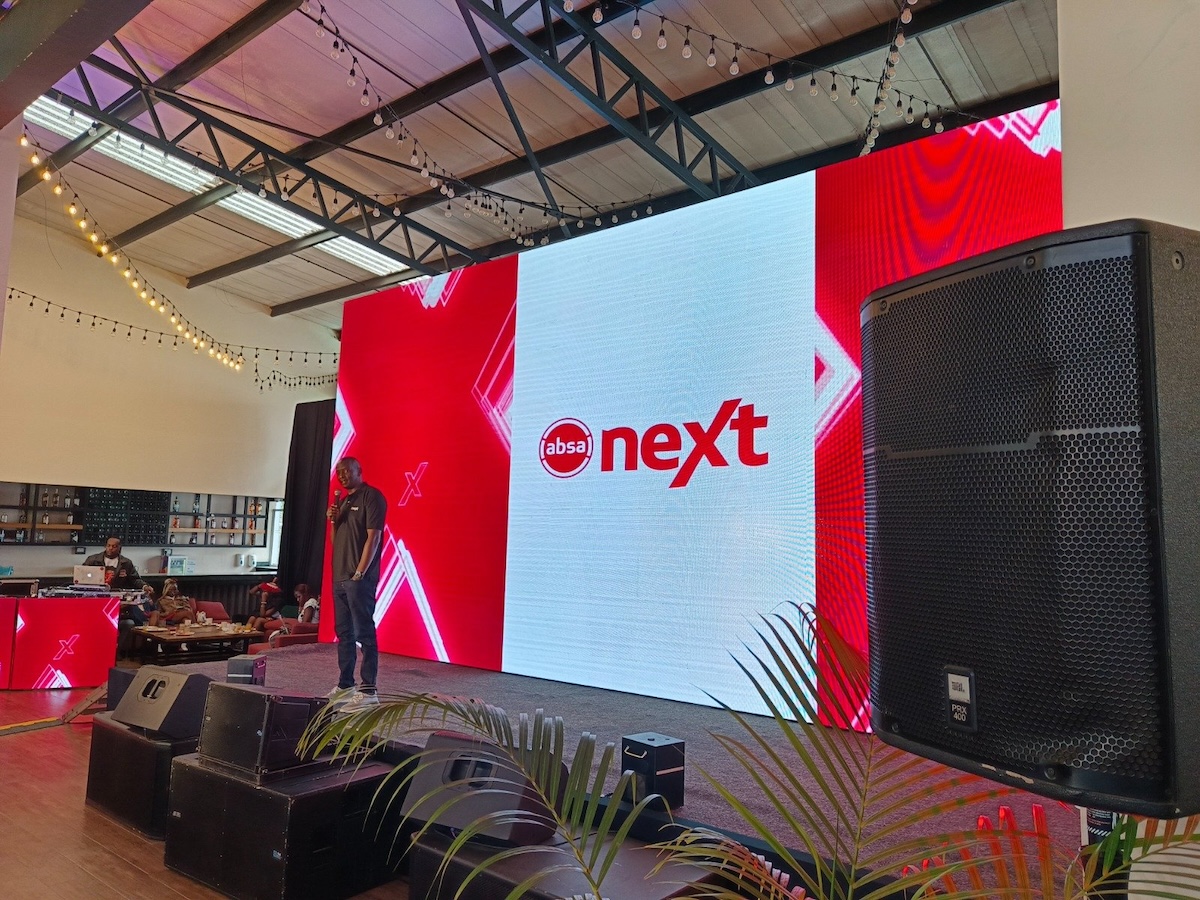
Absa Next is a new digital finance platform from Absa Bank Kenya that brings banking, payments, credit, savings, investments and business finance into one interface.
The app is open to Absa customers and non-customers, allowing users to access financial services without first holding a conventional Absa account. Its launch therefore raises a bigger question than what features sit inside the app: what exactly is Absa trying to become in a Kenyan financial market where banks, mobile-money platforms and fintechs increasingly compete for the same daily transactions?
The answer starts with the way Absa has approached digital banking over the past several years. The bank has been spending between KSh2 billion and KSh3 billion a year on technology, while about 94% of customer transactions were already taking place outside physical branches by 2025. Absa has also digitised 71% of customer processes.
That context matters because Absa Next is not a response to a bank that has yet to move online. It is an attempt to build a different digital relationship with customers who already expect to manage money through their phones, while also reaching people who may not consider Absa their primary financial institution.
Absa Next is built around the customer’s financial life
The product emerged from a question Absa says its digital banking team began asking about three years ago: what should the next phase of the bank look like? Steve Omamo, Absa’s head of digital banking, said the team eventually concluded that it could not answer that question internally and had to involve customers in the process.
The bank ran customer research, focus groups and product development sessions before moving through prototypes and successive versions of the platform. More than 50 customers, entrepreneurs, creators and other participants were involved in the co-creation process described by Absa at the launch. The resulting proposition was organised around two ideas that came up repeatedly in the research: convenience and progress.
That approach helps explain the structure of the app. Instead of presenting the customer with a collection of traditional banking departments, Absa Next puts everyday financial actions at the centre. Users can pay bills, send and receive money, split expenses, save towards goals, manage group contributions, access credit and view financial information from more than one institution.
Yusuf Omari, Absa Bank Kenya’s managing director and CEO, described the proposition in terms of both lifestyle and lifecycle. A customer might be finishing university, starting a business, managing a household, investing for the first time or juggling several sources of income. The product is designed around those activities rather than around a single banking product.
That distinction is important in Kenya because financial behaviour already cuts across institutional boundaries. A customer can receive income through a bank, collect business payments through M-PESA, save through a money market fund, borrow through a digital lender and use a different bank’s card for purchases. TechTrends’ reporting on Kenya’s payments market has documented how interoperability, PesaLink, APIs, QR payments and mobile wallets are making those boundaries easier for customers to cross.
Absa Next is therefore entering a market where the financial institution that owns the customer’s account does not necessarily own the customer’s financial activity.
Why Absa built another digital platform
Absa’s existing digital banking operation already handles most of the bank’s customer transactions. The case for Absa Next therefore rests on a different proposition: bringing more of the customer’s financial life into one digital environment and making the platform accessible to people who are not already Absa customers.
That puts the product closer to a digital financial platform than a conventional mobile banking front end. Customers can link Visa cards issued by other banks and bring accounts from other financial institutions into a consolidated view. The platform also combines personal and business finances, giving an individual who runs a small business the ability to manage both sides of their financial life under one login.
The strategy fits a broader direction visible across Absa Group. Sitoyo Lopokoiyit, who joined Absa after leading M-PESA Africa, has been associated with a wider push to place financial services closer to the platforms and activities where customers already spend their time. TechTrends’ reporting on Absa’s fintech partnerships in South Africa found the group pursuing partnerships and digital distribution as part of a broader effort to strengthen customer relationships.
His role makes the Kenyan launch particularly significant. Lopokoiyit brings experience from a mobile-money platform that became deeply embedded in everyday financial behaviour, while Absa brings a regulated banking balance sheet, lending capability, investment products and a regional footprint.
The combination reflects a wider contest across African finance. Banks are competing with telecom-led wallets and fintech platforms that have become part of daily commerce, while telecom operators are expanding deeper into savings, credit, investments and merchant services. TechTrends’ reporting on the movement of executives between banking and mobile money has documented how the boundaries between the sectors are becoming increasingly connected.
What sits inside Absa Next
At launch, Absa Next brings together several financial functions that customers would traditionally access through separate products.
Users can borrow from KSh500 to KSh1 million for qualifying personal and business needs, while Absa says its credit assessment can draw on broader financial behaviour and data rather than relying only on conventional banking history. The app also offers savings products with rates of up to 7%, while investment products have been presented with potential returns of up to 16%. The investment proposition should be understood according to the products actually available at the time of use, rather than as a guaranteed return.
The app also puts considerable attention on social and group finance. Customers can create Chamas, track contributions and manage group goals, while Harambee groups provide a looser structure for collective fundraising. Bill splitting allows users to divide expenses among friends or family, while savings goals and challenges add a social element to setting money aside.
Those features are particularly relevant in Kenya because collective financial behaviour remains widespread. Informal groups, Chamas and welfare arrangements already form part of how households save and respond to financial needs. Digitising those activities therefore addresses a recognisable local behaviour rather than importing a generic feature from another market.
The business proposition extends the same logic to small enterprises. Absa’s Business Banking Director Renato Duza identified onboarding, collections, payments and credit as some of the recurring problems facing SMEs. Absa Next’s business wallet is intended to bring those activities together, including collections, payments and access to credit for qualifying businesses.
That matters because the SME owner is often also the individual managing the business’s household finances. Separating those activities across multiple applications creates administrative friction. Absa Next’s attempt to put personal and business finances under one digital relationship is therefore one of the more consequential parts of the product.
The technology behind the platform
The customer experience is designed to look simple, but Absa says the technology underneath it has been built as a separate cloud-based platform.
Julius Camo, Absa Bank Kenya’s chief operating and digital officer, said the product was developed using a DevSecOps approach, with security incorporated into the development process rather than treated as a final layer. AWS provides the cloud infrastructure, while Happiest Minds has been involved in application development.
Moses Akundi, Absa’s chief information technology officer, described the development process as iterative. The product had moved through earlier versions before reaching the launch build, and the bank expects further changes as customers use the platform and provide feedback.
The cloud architecture also gives Absa room to scale capacity according to demand. That is important for a platform intended to handle financial activity at very different levels, from ordinary daily transactions to major spikes in demand.
This technology architecture connects with the investment Absa Kenya has already made in digital infrastructure. The bank’s technology spending and high proportion of alternative-channel transactions show that the foundation for digital banking was already substantial before Absa Next arrived.
The difference is where that infrastructure is being applied. Absa Next gives Absa a new environment in which the bank can design the customer experience around a broader set of financial activities.
Why SMEs and group finance matter
The most distinctive parts of Absa Next are arguably those closest to how Kenyans actually organise money.
The Chama tools recognise that financial activity can be collective. The SME tools recognise that a business owner may need payments, collections, working capital and financial visibility in the same place. The ability to link external accounts recognises that customers already use several financial institutions.
Together, those features point toward a platform designed to accommodate the way financial lives already work rather than forcing customers into a single institutional relationship.
That approach also fits the wider Kenyan payments market. Digital payments now span mobile money, cards, QR codes, bank transfers and interoperable account-to-account payments. Businesses increasingly depend on digital collections and settlement, while APIs connect financial services with accounting, payroll, e-commerce and merchant-management systems.
Absa Next is arriving into that environment with the ambition of becoming one of the places where those activities can be viewed and managed.
Absa Next enters a crowded digital finance market
The proposition has to be judged against a market that has already moved well beyond conventional mobile banking.
KCB’s Vooma, Equity’s digital channels, I&M Bank’s digital account opening and lending proposition, Family Bank’s PesaPap, Stanbic’s investment services and the country’s mobile-money platforms have all pushed financial services further into the phone.
TechTrends’ September reporting on Kenyan banking showed that digital competition is already moving beyond the traditional contest for loan customers. Lower interest rates are placing greater value on deposits, payments, merchant relationships, digital distribution and customer data. Banks are therefore looking for ways to become more relevant to a larger share of the financial activity surrounding each customer.
That makes Absa’s claim that it is offering an integrated digital financial solution more useful when understood as a strategic ambition than as a statement that individual features are unprecedented. The competitive question is whether combining these services in one open platform creates enough additional value to change customer behaviour.
The Timiza and existing-app question
There is also an unresolved question inside Absa itself.
Absa Next has launched alongside the bank’s existing mobile banking application and Timiza, the mobile financial service that Absa inherited from the Barclays era. Timiza has historically been closely associated with M-PESA, short-term credit and simplified financial services.
Absa executives have said the products will initially coexist while the bank assesses how customers use them. That leaves open the longer-term relationship between the three digital propositions.
That decision will matter because the success of Absa Next will depend partly on whether it creates a clear reason for customers to use it rather than simply adding another application to an already crowded financial environment.
It also raises a broader product question. If Absa Next is intended to become the bank’s principal digital relationship with the next generation of customers, the bank will eventually have to decide how much of its digital architecture should remain separated by legacy product and customer segment.
Kenya is the proving ground
Absa has made clear that Kenya is more than the launch market for the platform. The bank has positioned the Kenyan build as a potential blueprint for digital banking across the wider Absa Group.
That ambition fits the bank’s broader view of Kenya as a market where mobile money, banking, payments and fintech have developed at unusual speed. TechTrends reported in June that Absa’s deeper commitment to its Kenyan franchise reflects the country’s strategic importance within the group’s African operations.
Lopokoiyit’s comments about Tanzania on October 4 reinforce that wider perspective. He has described Tanzania as an important mobile-money innovation market while arguing that African financial services need to adapt to the specific behaviour and economic structures of each market.
That makes the Kenyan development process around Absa Next particularly relevant. If the platform works in a market where customers already have strong relationships with M-PESA, banks, fintechs and informal financial groups, Absa will have a useful model to adapt elsewhere.
The export question, however, will depend on what actually works in Kenya. A feature that succeeds because it reflects a Kenyan behaviour cannot automatically be transplanted into another market with different payment infrastructure, regulation or customer habits.
What Absa Next still has to prove
The launch establishes the proposition. It does not yet establish the outcome.
Absa will need to show that customers who download the app actually use it regularly, that non-Absa customers see enough value to make it part of their financial lives, and that the combination of services creates a deeper relationship with the bank.
The bank has also set a substantial customer-acquisition ambition. Reports around the launch put its target at one million customers during the first year.
That will provide a useful early measure of market interest, but customer numbers alone will not answer the larger question. The more revealing indicators will be how often customers transact, how much money moves through the platform, whether SMEs use the business tools, whether customers adopt savings and investment products, and whether the app becomes a genuine financial hub rather than another place to check a balance.
That is ultimately what makes Absa Next worth watching.
Absa has already invested heavily in the technology required to operate a digital bank. It now has a platform that brings more of the customer’s financial activity into one place, with open banking, credit, savings, group finance, business services and payments sitting alongside the traditional banking relationship.
The harder part begins after launch. Absa has to persuade customers who already have plenty of ways to move, save, borrow and spend money that Absa Next deserves a permanent place in that routine. If it succeeds, the significance of the platform will extend beyond a new banking app. It will show how a large African bank can use its existing scale and infrastructure to compete for the digital financial relationship itself.
Real ESG impact doesn’t happen in panels alone, it happens in the rooms where financiers, operators, and policymakers actually align. Our GreenShift Forum 2026 cuts the noise, bringing together the people rewiring Africa’s sustainability and energy frameworks for one focused day in Nairobi. Secure your seat.
Go to TECHTRENDSKE.co.ke for more tech and business news from the African continent and across the world.
Follow us on WhatsApp, Telegram, Twitter, and Facebook, or subscribe to our weekly newsletter to ensure you don’t miss out on any future updates. Send tips to info@techtrendsmedia.co.ke