What Abdi Mohamed inherits as he takes over the top job at I&M Bank
Abdi Mohamed takes over I&M as banking rivalry shifts toward digital scale

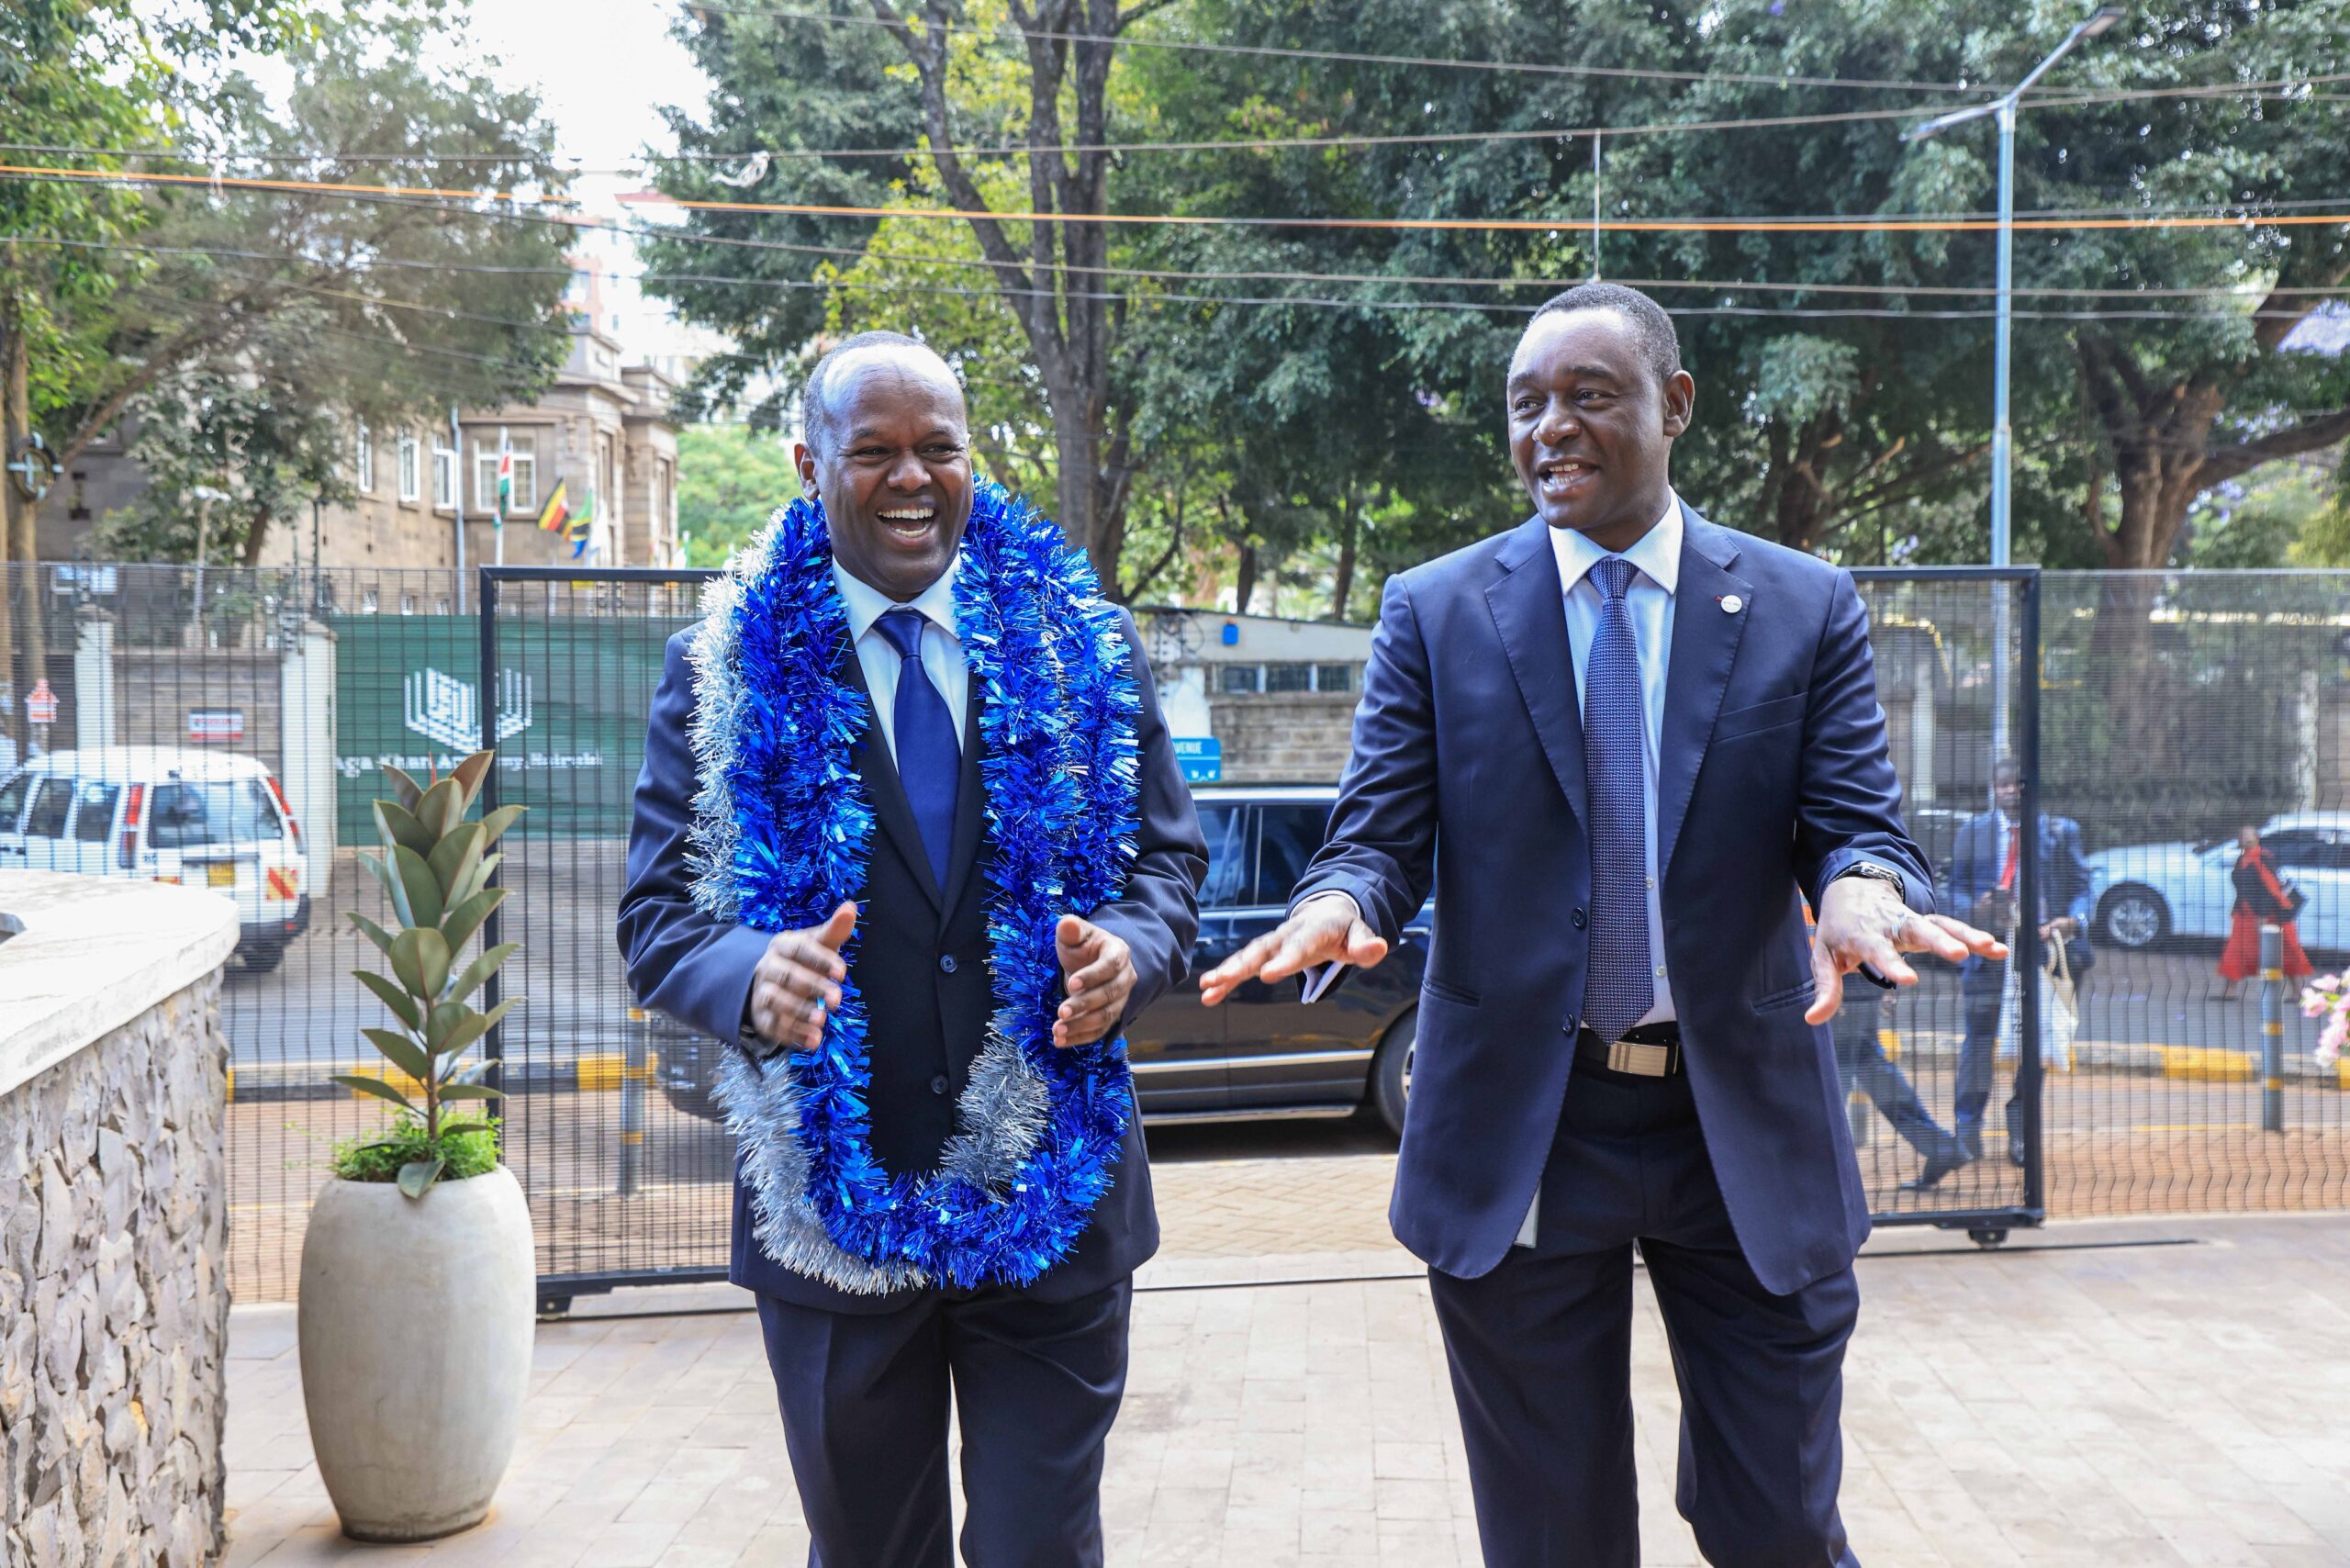
Former Absa Bank Kenya CEO Abdi Mohamed has taken charge of I&M Bank earlier than initially expected, moving directly from one of Kenya’s largest lenders to a smaller rival that is rapidly expanding its retail, SME and digital banking operations.
Mohamed formally became I&M Bank Kenya CEO on October 5 after receiving regulatory approval. He had originally been expected to remain on gardening leave until December, but Absa ended the arrangement in late September following the appointment of Yusuf Omari as its substantive CEO.
The accelerated transition adds another dimension to an executive move that was already significant. Mohamed spent more than three decades at Absa and its predecessor Barclays, including senior leadership roles in Tanzania and Kenya. He is now taking over a bank whose Kenyan operation is approaching Absa in some important measures while pursuing a different route to growth built around retail customers, small businesses, digital channels and regional expansion.
I&M is therefore not simply gaining a new CEO. It is bringing in an executive who knows one of its closest competitors from the inside at a time when the two institutions are increasingly pursuing similar customer economics.
Mohamed is joining a bank that is already moving
I&M has spent much of 2026 expanding a strategy that puts greater emphasis on customer numbers, transaction activity and the range of services attached to each relationship.
The group reported a 22 percent increase in net profit to KSh10.2 billion for the six months to June, while profit before tax rose 15 percent to KSh13.5 billion. Operating income increased 23 percent to KSh33.7 billion, total assets reached KSh746 billion, loans grew 15 percent to KSh334 billion and customer deposits rose 18 percent to KSh505 billion.
Those numbers give Mohamed a substantial platform. But they also explain why his mandate is broader than simply increasing lending.
I&M is trying to make more of each customer relationship through payments, foreign exchange, remittances, wealth management, insurance and digital credit alongside traditional banking.
The strategy reflects a banking market where relying on interest income alone is becoming increasingly difficult. Customer acquisition, low-cost deposits, payments and fee-generating services are becoming more important to the economics of scale.
I&M’s Kenyan retail and business banking loan book has already crossed KSh100 billion. The bank is trying to turn those relationships into broader financial relationships in which a customer can borrow, save, receive payments, transfer money, exchange currencies and access other services from the same institution.
For Mohamed, the challenge is therefore to increase the economic value of the customer base rather than simply make the balance sheet larger.
I&M is getting closer to Absa in scale
The competitive significance of Mohamed’s move becomes clearer when the two Kenyan operations are compared.
Absa Bank Kenya had assets of about KSh571 billion and a loan book of KSh303 billion, while I&M Bank Kenya had approximately KSh550 billion in assets and KSh250 billion in loans. Customer deposits at both institutions stood at roughly KSh396 billion in the figures provided.
I&M remains smaller in lending and overall scale, but the gap is not large enough to make the move a simple case of an executive leaving a much larger bank for a distant challenger.
The two institutions are also competing for many of the same areas of future growth.
I&M is pushing further into retail and SME banking, digital onboarding and transaction-led services. Absa has been pursuing a similar shift, including through Absa Next, its digital platform combining banking, payments, credit, savings and investments and extending its reach to people who do not already bank with the institution.
That makes Mohamed’s previous experience particularly relevant. He is arriving at I&M with detailed knowledge of how a larger competitor operates while that competitor is itself changing its approach to digital financial services.
I&M’s digital strategy is already producing scale
The bank’s digital expansion is one of the clearest examples of the strategy Mohamed inherits.
By September, about 25,000 people were opening I&M accounts each month without visiting a branch. The onboarding process uses national identification, smartphone verification and liveness checks, allowing customers to open accounts remotely and fund them through mobile money. About 85 percent of I&M’s retail accounts were being opened digitally.
The bank has also reported that about 90 percent of its customers are digitally active, up from roughly 80 percent a year earlier.
That changes the economics of customer acquisition. A bank does not need to expand its physical footprint at the same rate if customers can open accounts, transfer money and access services through digital channels.
But acquisition is only the beginning.
I&M has been trying to give customers reasons to keep using those accounts. The bank made transfers to M-PESA and Airtel Money free and has expanded self-service capabilities across its digital channels.
It has also built digital credit around customer data. Its Kenyan short-term digital loan has disbursed close to KSh700 million and is being adapted into working-capital financing for small traders. In Tanzania, the Kamilisha overdraft product has reached about seven million Airtel subscribers and disbursed close to TZS700 billion.
I&M’s credit models combine income proxies, credit-reference information and customer behaviour, including transaction activity inside its digital ecosystem.
That creates a direct connection between digital acquisition, payments and lending.
The more active the customer, the more information the bank can potentially use to understand financial behaviour and offer additional products. The same activity can generate transaction revenue and deepen the relationship.
That is the model Mohamed now has to scale.
The regional business is becoming too important to ignore
I&M’s expansion also extends well beyond Kenya.
Its subsidiaries in Rwanda, Uganda and Tanzania contributed 33 percent of group profit before tax in the first half of 2026, up from 25 percent a year earlier. The regional operations are therefore becoming a meaningful contributor to group earnings rather than simply supporting the Kenyan business.
That creates an opportunity to spread technology investment and operating capabilities across several markets.
I&M’s digital teams already develop platforms and infrastructure in Kenya that can support the wider group. Its digital business leadership has been working across Kenya, Tanzania, Uganda, Rwanda and Mauritius, allowing technology and product capabilities to be reused rather than rebuilt independently in every market.
Mohamed’s previous experience in Tanzania becomes relevant here. His career at Absa included leading the Tanzanian operation before he moved to Kenya, giving him experience of managing outside the group’s home market.
The opportunity is to use that regional experience to improve scale and consistency across I&M’s markets.
The complication is that customers, regulators, payment systems and competitive conditions differ from one country to another. Technology can be shared, but products and distribution still need local adaptation.
Absa is changing at the same time
The competitive backdrop is important because Absa is not standing still after Mohamed’s departure.
On October 7, Absa Group appointed former NCBA and LOOP DFS executive Eric Muriuki as Managing Executive for Pan-African Growth Strategy, Platforms and Digital Ventures. His portfolio covers digital platforms, new ventures and growth across the group’s African operations.
The appointment follows a broader reshaping of Absa’s leadership during 2026, including changes across corporate and investment banking, personal and private banking, business banking and Kenya.
Absa has also launched Absa Next in Kenya, a digital platform that combines banking, payments, lending, savings and investments and is available to both existing Absa customers and people outside the bank’s traditional customer base.
The significance for I&M is straightforward.
Mohamed has moved into an institution trying to expand its digital reach and customer base at the same time his former employer is reorganising around many of the same priorities.
The competitive contest is no longer just about who has the bigger branch network or loan book. Banks are increasingly competing for the customer’s everyday financial activity.
The battle is moving beyond the bank account
The shift is visible across Kenya’s banking sector.
Customers can receive income through a bank, move money to M-PESA or Airtel Money, make payments through a merchant platform, borrow through a digital lender and invest through a separate financial application.
The bank account may remain central to that relationship, but it no longer guarantees that the bank controls the customer’s daily financial activity.
That is why I&M’s digital strategy matters beyond the number of accounts it opens.
The bank wants to capture more of the transactions around the customer relationship. Payments can create fee income and behavioural data. Deposits provide funding. Digital lending creates another revenue stream. Insurance, wealth management, foreign exchange and remittances can add further income without relying entirely on the traditional lending spread.
Absa is pursuing a similar logic through its own digital platforms.
The competition is therefore increasingly about who can build the most useful financial ecosystem around the customer while keeping acquisition costs, credit losses and technology spending under control.
Scale is not enough
This is where Mohamed’s biggest challenge lies.
I&M’s group numbers are strong, but the Kenyan business also faces rising costs and provisions. In the first half of 2026, the Kenyan operation accounted for the majority of group assets and profit before tax, but higher provisions and operating expenses put pressure on its earnings performance.
That creates a tension between expansion and returns.
Digital banking can lower the cost of acquiring and serving customers, but technology requires investment. Retail and SME lending can expand the addressable market, but smaller borrowers can introduce different credit risks. Regional expansion can diversify earnings, but it also adds management complexity.
The bank therefore needs the additional scale to produce better economics.
For Mohamed, that means converting digital accounts into active relationships, increasing transaction volumes, growing deposits efficiently, maintaining disciplined credit underwriting and finding more revenue from services beyond lending.
It also means making sure I&M’s regional operations continue to contribute to group earnings without allowing the complexity of multiple markets to dilute management focus.
Mohamed inherits a growth strategy, not a blank page
The timing of his appointment makes the task particularly interesting.
He is taking over after a period in which I&M has already invested in digital infrastructure, expanded retail and SME banking, grown its regional earnings contribution and built a customer acquisition model that increasingly operates outside branches.
At the same time, he is moving from an Absa operation that is pursuing its own digital transformation and reshaping its Pan-African leadership.
The two banks are not identical. Absa remains larger in Kenya, while I&M has a different balance of regional operations and a different competitive position. But their strategies are converging around many of the same questions: how to acquire customers digitally, how to deepen transaction relationships, how to use data responsibly, how to grow fee income and how to make technology investments produce measurable returns.
That makes Mohamed’s appointment more consequential than a routine CEO transition.
He knows the institution he has left. He now has to make a smaller rival move faster.
I&M’s next stage of growth will ultimately be judged not by how many new accounts it opens or how quickly its balance sheet expands, but by whether those customers become active, profitable relationships and whether the bank can translate its growing regional and digital footprint into stronger returns.
For Mohamed, that is the real assignment at I&M.
Real ESG impact doesn’t happen in panels alone, it happens in the rooms where financiers, operators, and policymakers actually align. Our GreenShift Forum 2026 cuts the noise, bringing together the people rewiring Africa’s sustainability and energy frameworks for one focused day in Nairobi. Secure your seat.
Go to TECHTRENDSKE.co.ke for more tech and business news from the African continent and across the world.
Follow us on WhatsApp, Telegram, Twitter, and Facebook, or subscribe to our weekly newsletter to ensure you don’t miss out on any future updates. Send tips to info@techtrendsmedia.co.ke