Inside I&M Bank’s push to go ‘digital fast’
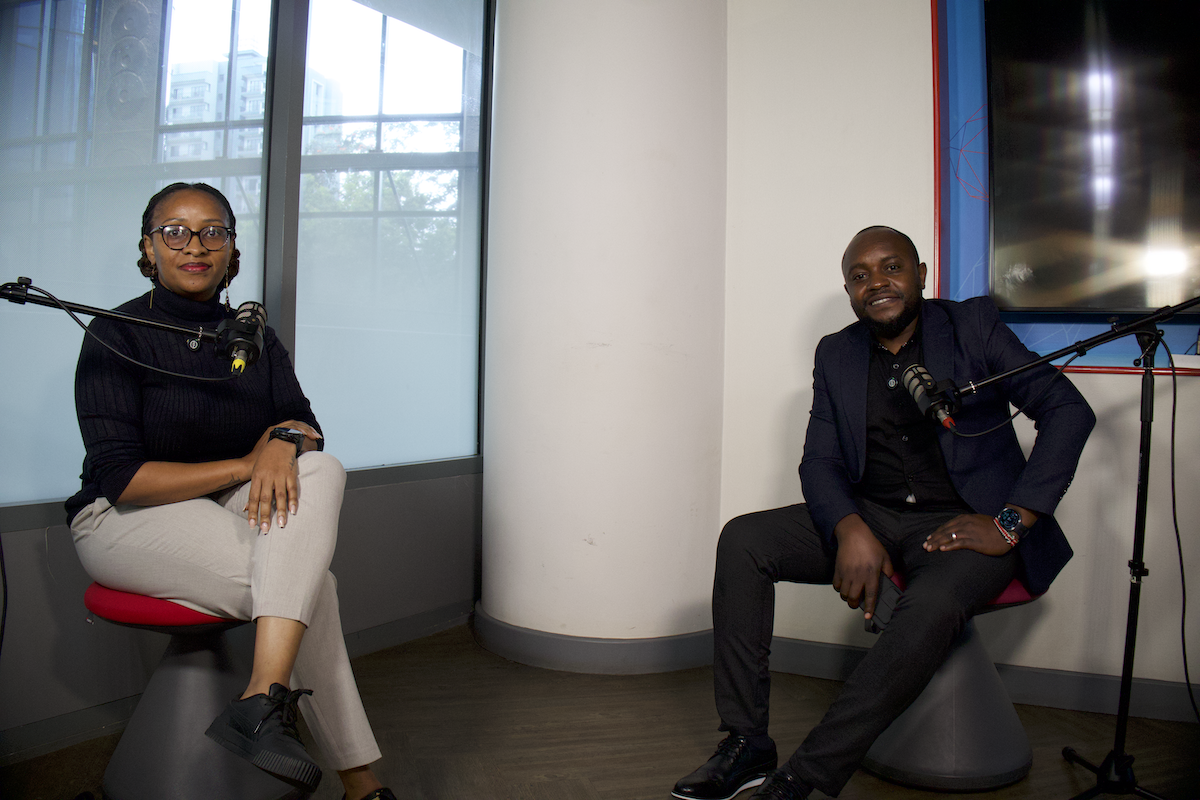
Long seen as a bank for big business, I&M is using five-minute onboarding, fee-free mobile money transfers and data-driven loans to win retail and SME customers across East Africa. Group Director for Digital Business Eunice Gatama explains the strategy on The TechTrends Podcast.


Every month, about 25,000 people open an I&M Bank account without filling in a form. They need only a national ID and a smartphone, and a liveness check confirms they are who they claim to be. About five minutes later, they are funding the account through M-PESA.
For a lender whose name was built on corporate and mid-sized business clients, this is a big change. Retail banking at I&M once meant serving the employees of its corporate customers. Now it is a core strategic pillar, and digital channels are what make that possible.
“Without that, bringing 25,000 forms into the branches for people to open accounts would have been impossible,” Eunice Gatama, Group Director for Digital Business at I&M Group, said on The TechTrends Podcast.
Today, about 85% of the bank’s retail accounts are opened digitally.
Gatama sums up the philosophy in two words: digital fast. She oversees I&M’s app, web and USSD channels across Kenya, Tanzania, Uganda, Rwanda and Mauritius, along with the products built on them and the partnerships behind them. From Nairobi, she works with country CEOs so that customers who bank across borders get the same experience everywhere. The Kenyan digital factory’s engineers and quality assurance teams serve the rest of the group, so each market does not have to build the same things again.
She insists the approach begins with the plumbing rather than the product.
“We’re really trying to say we need to be digital fast, and being digital fast means your channels are working,” she said. “A digital dream without the proper technical infrastructure or modern technology is really just that, just a dream.”
Signing customers up turned out to be the easy part. Giving them a reason to use the account was harder. I&M’s answer was to make transfers to M-PESA and Airtel Money free. Most of the industry went back to charging after the Covid-era waiver ended, and Gatama admits the decision surprised many peers.
“We know the pain of transaction costs. When the government had said stop charging during COVID, we later said, why then start charging?” she said. “That’s why customers are opening accounts with I&M, because it makes sense.”
Credit came next. Gatama describes Kenyans as natural hustlers who need quick access to funds, and says any bank serious about the mass market has to meet that need. I&M’s digital short-term loan asks customers to opt in. They are credit scored and given a limit that grows with responsible use, with no paperwork involved. The product has disbursed close to KES 700 million (about USD 5.4 million) in Kenya. The bank is now adapting it into a working capital facility for small traders, starting in the counties where it has recently opened branches.
The confidence behind the product comes from Tanzania. Since 2021, I&M has partnered with a fintech and Airtel to offer Kamilisha, an overdraft service similar to Safaricom’s Fuliza. It has reached about seven million Airtel subscribers and disbursed close to TZS 700 billion (roughly USD 270 million), with a non-performing loan ratio of about 5.2%.
“That has really shown us the power of data to understand your customers and offer them the right product is central to scaling in digital,” Gatama said.
I&M’s scoring models combine income proxies, credit reference bureau history and in-app behaviour, including payments for electricity, water and Zuku. That only works if customers are active in the app, and increasingly they are. According to the bank’s latest results, 90% of I&M customers are now digitally active, up from about 80% a year earlier.
Gatama gives three reasons for the jump. The first is more stable channels, built with the bank’s ICT team. The second is moving everyday services such as username resets and cheque stoppages out of branches and into self-service. The third is branch staff showing walk-in customers what they can already do on their phones. The bank has also made USSD available from the day an account is opened, recognising that many upcountry customers still use feature phones.
More data brings more responsibility, and Gatama is clear that data protection is not optional. I&M runs an enterprise data office with analytics, data engineering and governance teams. The governance team tracks data quality scores in every market, and a data protection officer checks compliance. Borrowers are told how their data will be used before they consent, and that consent is recorded. Fintech partners must meet minimum standards on how they collect and handle customer information.
The next frontier is hyper-personalisation. That means predicting the next product a customer needs, and making sure a call centre agent recognises a returning caller instead of putting them through identity checks again.
Beyond that, Gatama sees I&M Bank’s growth over the next three to five years depending on partners rather than competing with them. The bank’s strategy includes a pillar on ecosystem leadership: offering lending and payment rails to fintechs in agriculture, edtech and e-commerce, and using those relationships to enter new markets.
“We cannot play in this financial services space alone,” she said. “As an industry, we have a lot to do to understand what these fintechs are doing, how they’re doing it and how we can partner with them to offer banking services.”
Real ESG impact doesn’t happen in panels alone, it happens in the rooms where financiers, operators, and policymakers actually align. Our GreenShift Forum 2026 cuts the noise, bringing together the people rewiring Africa’s sustainability and energy frameworks for one focused day in Nairobi. Secure your seat.
Go to TECHTRENDSKE.co.ke for more tech and business news from the African continent and across the world.
Follow us on WhatsApp, Telegram, Twitter, and Facebook, or subscribe to our weekly newsletter to ensure you don’t miss out on any future updates. Send tips to info@techtrendsmedia.co.ke