Starlink reaches 27,616 Kenyan users, but capacity constraints are keeping new customers waiting

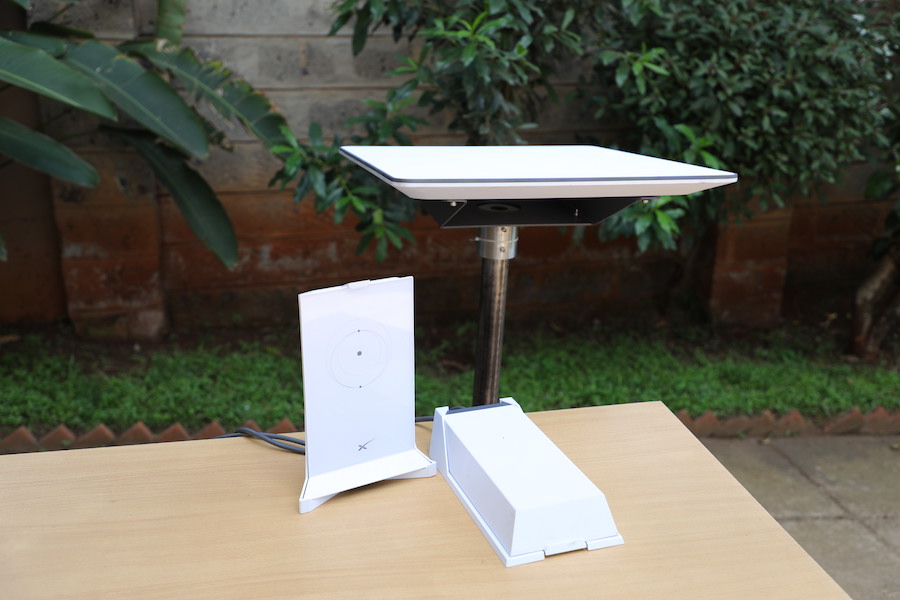
Starlink’s subscriber base in Kenya jumped 58.5% in a year to hit 27,616 by June 2026—up from 17,425. But that rapid surge in popularity has come with a catch: network capacity is stretched so thin that new residential customers in eight major counties are currently stuck on waiting lists.
Prospective customers in Nairobi, Kiambu, Mombasa, Machakos, Murang’a, Kirinyaga, Kwale and Kilifi are being directed to a waiting list instead of being allowed to complete new residential orders. Starlink has previously used the same approach when service areas reach available network capacity, asking customers to place a deposit and wait until additional capacity can be added. The latest restriction is therefore less a question of whether Kenyans want satellite broadband and more a question of how quickly the network can accommodate demand in particular areas.
Starlink adds 10,191 Kenyan customers in a year
The latest sector data from the Communications Authority of Kenya puts Starlink at 27,616 fixed internet subscriptions by the end of June, giving it about one percent of Kenya’s 2.84 million fixed connections. Its position is far stronger within satellite broadband, where Starlink accounts for 27,616 of 27,695 subscriptions, or about 99.7 percent of the segment.
That distinction is important. Starlink remains a small player in Kenya’s overall fixed broadband market, where fibre continues to carry the largest share of connections. Fibre subscriptions reached 1.57 million by June, up 29.7 percent from a year earlier, while the wider fixed internet market grew 32.4 percent to 2.84 million connections. Starlink’s growth is therefore taking place inside a broadband market that is expanding across several technologies rather than replacing the terrestrial networks already serving most homes and businesses.
The numbers nevertheless show how quickly satellite broadband has established itself. Starlink’s 10,191 additional subscriptions over 12 months are enough to make the service a meaningful part of Kenya’s connectivity conversation, particularly in places where laying fibre to individual premises is expensive, slow or difficult.
Capacity limits return in eight counties
The current restrictions also have a recent precedent. Starlink suspended new subscriptions in Nairobi and surrounding counties in late 2024 after demand exceeded available network capacity. New orders resumed in July 2025 after the company expanded capacity, ending a freeze that had lasted about seven months.
The recurrence matters because it shows that satellite connectivity does not eliminate the basic capacity problem faced by conventional networks. Starlink can bypass much of the terrestrial last-mile infrastructure required to connect a home, but the satellite beams and supporting network infrastructure serving a particular area still have finite capacity. TechTrendsKE’s earlier reporting on the 2026 restrictions found that the affected counties included some of Kenya’s busiest population and economic centres, where customer density can put greater pressure on available bandwidth.
The distinction between national growth and local capacity is crucial. Starlink can add thousands of subscribers across Kenya while restricting new orders in selected service areas because the capacity available to customers is determined partly by where those customers are located. The waiting list therefore provides a geographic picture of demand rather than evidence that the entire Kenyan network has reached its limit.
Speed performance adds another pressure point
The capacity issue has emerged alongside changes in Starlink’s measured performance. Ookla data reported by TechTrendsKE showed Starlink’s median download speed in Kenya at 34.55 Mbps in March 2026, compared with roughly 47 Mbps a year earlier. That is a decline of about 26.5 percent over the period, although the available data do not establish that subscriber growth alone caused the reduction.
The performance picture is more complicated than the download-speed number suggests. Starlink’s Nairobi Point of Presence sharply reduced latency, with reported round-trip times falling from about 296 milliseconds to roughly 39 milliseconds after local network infrastructure was activated. That improvement shows how much the user experience depends on what happens after traffic comes down from orbit.
Gateways, fibre backhaul, local routing and internet exchange infrastructure all affect how quickly data reaches its destination. The satellite therefore forms only one part of the connection. Starlink’s Kenyan experience demonstrates that expanding orbital capacity without adequate ground infrastructure would leave part of the network’s performance problem unresolved.
Kenya’s broadband market is expanding on several fronts
Starlink’s capacity constraints are unfolding while Kenya’s terrestrial broadband infrastructure is also growing. The fixed internet market added connections rapidly during the year to June, with fibre remaining the dominant access technology and wireless networks providing another route for homes and businesses. Total available international bandwidth also reached 28,950 Gbps, up 18.5 percent year-on-year, according to the latest sector data.
Mobile networks are undergoing their own infrastructure transition. By September, Kenya was preparing for the eventual phase-out of older 2G and 3G technologies as 4G and 5G adoption expanded. The broader market is therefore adding capacity through fibre, mobile networks, fixed wireless and satellite at the same time.
That gives consumers more alternatives than they had when Starlink first entered the Kenyan market in 2023. Fibre operators such as Safaricom, Jamii Telecommunications and Wananchi Group continue to hold much larger shares of the fixed broadband market, while smaller providers are competing through higher speeds, pricing and different deployment models. TechTrendsKE has also documented the growth of Fibre to the Room services, which are designed to improve connectivity inside larger homes as connected devices and high-bandwidth applications become more common.
Starlink’s proposition remains particularly relevant where terrestrial last-mile infrastructure is difficult to deploy. Its use in Murang’a’s public telemedicine programme, where Paratus and Starlink are supporting connectivity across 170 health facilities, illustrates how satellite broadband can serve institutional and rural applications beyond conventional residential subscriptions.
Satellite connectivity is moving beyond home broadband
The Kenyan satellite market is also becoming more varied. Airtel Kenya has completed trials of Starlink Direct-to-Cell technology and is awaiting regulatory approval for a service that would allow compatible smartphones to connect directly to satellites when conventional terrestrial coverage is unavailable. Earlier trials demonstrated messaging and data services without requiring customers to install a Starlink terminal.
That model addresses a different problem from Starlink’s residential broadband service. A household using a Starlink dish requires a dedicated terminal and a clear view of the sky, while Direct-to-Cell is designed to extend connectivity to compatible mobile phones outside normal tower coverage. If approved, the service would place satellite connectivity alongside Kenya’s mobile network rather than compete with home fibre on the same terms.
The regional market is already moving in this direction. Paratus Uganda launched Starlink for enterprise customers in August, combining satellite access with its existing terrestrial network and cross-border connectivity infrastructure. The company described the service as part of a broader multi-layered network strategy serving sectors such as mining, healthcare, tourism, NGOs and government.
Amazon Leo prepares to challenge Starlink
The competitive landscape is also about to become more crowded. Amazon has applied through Amazon Kuiper Kenya Limited for regulatory approval to deploy its satellite network in Kenya and has pursued plans for gateway infrastructure that would connect the constellation to terrestrial networks. The company has also reached the initial commercial-service milestone for its Low Earth orbit constellation, although building a large-scale network requires much more than putting satellites into orbit.
Kenya’s importance to Amazon’s plans goes beyond the prospect of another consumer broadband provider. Gateway stations, fibre connections, internet exchanges and local routing determine how satellite traffic enters the internet, making the country’s terrestrial infrastructure relevant to any LEO operator that wants to deliver low-latency service at scale.
Amazon’s progress elsewhere in Africa also shows that there are several possible routes into the market. In South Africa, Amazon has partnered with Herotel to provide satellite broadband through an existing licensed internet provider, allowing the local operator to handle sales, installations and customer support while Amazon supplies satellite capacity.
For Kenya, the outcome will depend on regulatory approval, network deployment, pricing and how Amazon combines its orbital network with local infrastructure. It also gives consumers another potential satellite option at a time when Starlink is asking some prospective customers to wait.
Starlink’s next challenge is adding capacity
Starlink has already demonstrated that there is a market for satellite broadband in Kenya. Its 27,616 subscriptions and near-total share of the satellite segment provide the clearest evidence of that demand, while its one percent share of the wider fixed market shows that there is still considerable room for other connectivity technologies.
The immediate constraint is geographic capacity. New customers in eight counties are being held on waiting lists while Starlink works within the limits of the network serving those areas, repeating a pattern seen during the 2024-25 suspension. The company’s ability to add customers will therefore depend on how quickly it can expand satellite and ground capacity while maintaining service performance.
That challenge is arriving in a Kenyan broadband market that is building capacity through several layers at once. Fibre networks are expanding, mobile operators are moving customers toward 4G and 5G, data and international connectivity infrastructure is growing, and satellite providers are developing both fixed broadband and direct-to-device services.
Starlink remains the dominant satellite broadband provider in Kenya, but its latest waiting lists show that orbital connectivity still has physical and geographic limits. The next measure of its performance in the Kenyan market will therefore be how effectively it can turn strong demand into additional capacity without putting pressure on the experience of the customers it already serves.
Real ESG impact doesn’t happen in panels alone, it happens in the rooms where financiers, operators, and policymakers actually align. Our GreenShift Forum 2026 cuts the noise, bringing together the people rewiring Africa’s sustainability and energy frameworks for one focused day in Nairobi. Secure your seat.
Go to TECHTRENDSKE.co.ke for more tech and business news from the African continent and across the world.
Follow us on WhatsApp, Telegram, Twitter, and Facebook, or subscribe to our weekly newsletter to ensure you don’t miss out on any future updates. Send tips to info@techtrendsmedia.co.ke