Telkom challenges ownership rules that continue to complicate Starlink's entry into South Africa

South Africa’s telecommunications licensing framework is facing pressure from an established network operator that wants regulators to recognise alternative ways of meeting Black economic empowerment requirements.
Telkom has challenged the country’s telecom ownership rules, arguing that the current approach places too much emphasis on direct equity participation while overlooking other mechanisms recognised under the ICT Sector Codes.
The dispute has implications for how telecommunications companies attract investment, structure partnerships and expand network infrastructure. It also affects the conditions under which international satellite operators such as Starlink can enter the South African market.
In a submission to the Independent Communications Authority of South Africa (ICASA), Telkom questioned whether the Equity Regulations adequately reflect the broader empowerment framework established under the Broad-Based Black Economic Empowerment Act and the ICT Sector Codes.
The operator said the regulations introduce requirements beyond those contemplated in the existing empowerment framework. It also argued that they fail to recognise alternative ownership structures and other forms of compliance with transformation objectives.
Telkom maintains that the regulatory approach has created uncertainty for licence holders, increasing compliance costs and potentially discouraging investment in electronic communications networks.
Telkom questions the economics of telecom licensing requirements
The disagreement centres on regulations requiring telecommunications operators seeking relevant individual network and electronic communications licences to meet a minimum 30% ownership threshold for historically disadvantaged groups (HDGs).
The requirement also affects foreign telecommunications companies seeking to operate directly in South Africa. International operators must satisfy the ownership conditions or structure their market presence through an appropriate local intermediary.
Telkom argues that the framework does not adequately accommodate the different ways businesses can contribute to economic transformation.
The operator identified skills development, participation in local supply chains, infrastructure investment and research and innovation funding as alternative mechanisms through which telecommunications companies could advance B-BBEE objectives.
These proposals would give licence holders additional ways to demonstrate their contribution to transformation without making direct equity ownership the determining factor in every case.
Telkom said international best practice suggests empowerment objectives can be achieved through diverse mechanisms. It recommended that ICASA adopt requirements that are not excessively burdensome and can be applied consistently across all licence holders.
The company’s argument is also tied to the financial demands of telecommunications infrastructure. Network expansion requires substantial capital expenditure, while regulatory uncertainty can affect investment decisions and the cost of maintaining compliance.
Telkom warned that the lack of alignment between the licensing regulations and the broader empowerment framework had discouraged investment in digital infrastructure and electronic communications networks.
Its position is not that telecommunications operators should be exempt from transformation obligations. Rather, it wants the regulator to recognise a wider range of qualifying contributions and provide greater clarity on how those contributions are assessed.
Satellite operators are finding different routes into African markets
The ownership dispute has become particularly relevant as satellite internet providers seek access to markets where terrestrial networks remain expensive or difficult to deploy.
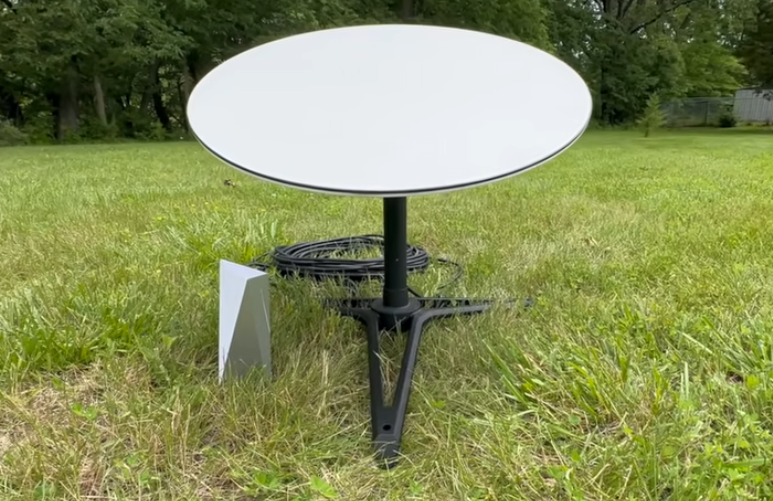
Starlink’s position in South Africa illustrates the consequences of the existing rules. The SpaceX-owned service has maintained that it cannot obtain the necessary licences without satisfying the 30% HDG ownership requirement or operating through an eligible local arrangement.
The company has supported proposals from communications minister Solly Malatsi to allow foreign operators to meet transformation requirements through Equity Equivalent Investment Programmes (EEIPs).
Under this approach, international businesses could make qualifying investments in areas such as education, infrastructure and skills development rather than transferring a direct ownership stake in their local operations.
Starlink has proposed connecting 5,000 predominantly rural schools across South Africa, a programme it said could benefit more than 2.4 million learners annually.
The proposal would provide high-speed internet connectivity to schools, particularly in areas where conventional telecommunications infrastructure has struggled to reach communities.
However, the commitment remains a proposed alternative to the ownership requirement, not an established operating programme or an approved licensing arrangement.
South Africa’s market also presents other possible models for satellite operators.
Amazon Leo announced a partnership with South African internet service provider Herotel in July 2026. Under the arrangement, Herotel would handle local sales, installation and customer support, while Amazon supplies satellite connectivity through its network. Commercial services were expected in 2027.
The arrangement illustrates how an international satellite provider can work with an established local telecommunications business to reach customers without building an entirely separate retail distribution operation.
It does not, however, establish that a commercial partnership automatically satisfies every licensing or ownership obligation.
Elsewhere in Africa, telecommunications operators are building relationships with Starlink around distribution and network services.
MTN Uganda and Paratus Uganda have introduced Starlink-related services, while Vodacom has pursued satellite connectivity for mobile network backhaul. Starlink has also partnered with Mawingu in Kenya, supporting connectivity for digital hubs, schools and farmer cooperatives.
These arrangements demonstrate that satellite operators can participate in telecommunications markets through different commercial relationships, including direct retail services, wholesale capacity and partnerships with existing network providers.
For South Africa, the challenge is determining how those arrangements should fit within licensing and empowerment requirements.
South Africa’s empowerment framework faces a regulatory test
The debate over alternative ownership arrangements predates Telkom’s submission.
Malatsi has sought to make EEIPs an acceptable mechanism through which foreign telecommunications operators can satisfy South Africa’s transformation objectives.
Starlink supports this position, arguing that multinational companies should be able to invest meaningfully in local development without having to surrender ownership of their businesses.
The company has pointed to the use of equity-equivalent arrangements in other industries as an example of how investment commitments can support transformation without requiring direct local equity participation.
The disagreement is partly about how economic participation should be measured.
Direct ownership gives qualifying shareholders an equity interest in a business, including the associated economic rights. Alternative investment programmes can finance infrastructure, education, local suppliers and skills development without necessarily transferring ownership or control of the licensed operator.
Those contributions can deliver different outcomes.
Connecting rural schools, for example, could improve access to educational resources and digital services. It would not automatically create ownership opportunities or give historically disadvantaged groups an equity interest in the telecommunications business supplying the service.
That distinction is central to the debate over whether EEIPs should be accepted as substitutes for direct ownership requirements.
Telkom’s submission brings the issue beyond the immediate Starlink dispute. Its recommendation is for a licensing framework that recognises different empowerment mechanisms while applying comparable requirements across the industry.
This would also affect how regulators assess new entrants against established telecommunications companies.
ICASA’s position leaves legislative reform in focus
The immediate regulatory obstacle is ICASA’s interpretation of the Electronic Communications Act.
After receiving Malatsi’s policy direction, the authority responded in May 2026 that it would not reconsider the relevant ownership regulations until the legislation was amended.
The regulator’s position has created a gap between the government’s preferred policy direction and the rules currently governing telecommunications licences.
The disagreement also involves the interpretation of wording in the Electronic Communications Act that allows for other appropriate conditions relating to historically disadvantaged ownership.
A previous amendment introduced this wording, which SpaceX has argued could provide a legal basis for recognising alternatives such as EEIPs.
ICASA has taken a different position, maintaining that legislative changes are necessary before it can reconsider the licensing requirements.
The interpretation of the legislation has now become the subject of separate legal proceedings brought by business advocacy organisation Sakeliga against ICASA on 11 November 2026.
The case concerns the regulator’s authority and the legal basis for the ownership conditions imposed on telecommunications operators.
It is separate from Telkom’s submission, although both developments concern the regulatory framework governing access to South Africa’s telecommunications market.
The outcome could influence the extent to which ICASA can adjust licensing conditions without further amendments to the legislation.
Telkom wants equal obligations across the telecommunications industry
Telkom’s position also needs to be considered against ICASA’s wider review of individual electronic communications network licences.
The authority has been examining whether additional I-ECNS licences should be issued and how changes to the licensing framework could affect competition, network deployment and universal access.
This inquiry is relevant to the arrival of additional satellite operators, including Starlink, Amazon Leo, Eutelsat OneWeb, Spacesail and Avanti Communications.
Telkom has argued that new satellite operators should face the same licence conditions and social obligations as existing telecommunications businesses.
That position introduces an important distinction between relaxing ownership requirements and giving incoming operators preferential treatment.
The company wants greater flexibility in how empowerment obligations are met, but it also wants regulatory parity between established operators and new entrants.
This matters because satellite connectivity is becoming part of the wider telecommunications infrastructure market rather than operating as an isolated service.
Operators can supply broadband directly to households and businesses, provide capacity to local internet service providers or support mobile networks through backhaul services. Each arrangement has different implications for infrastructure investment, competition and the relationship between local businesses and international technology providers.
Kenya’s experience offers one indication of how quickly this market is developing. Starlink had 27,616 subscriptions in the country by June 2026, according to Communications Authority figures reported by TechTrendsKE. Its subscriptions grew 58.5% year on year, although the service represented only a small proportion of Kenya’s wider fixed internet market.
The Kenyan market also illustrates the infrastructure limitations satellite operators face. Subscriber growth has coincided with capacity constraints and waiting lists in several counties, demonstrating that market entry alone does not guarantee sufficient network capacity or reliable service delivery.
For South Africa, the licensing debate therefore extends beyond whether foreign satellite companies should be permitted to operate. It concerns the conditions under which they enter, the obligations they carry and the extent to which their investments contribute to the domestic telecommunications industry.
Telkom’s submission places those questions within a wider discussion about the relationship between economic transformation and infrastructure investment.
The decision facing South African regulators is how to accommodate different forms of participation without weakening the objectives of the country’s empowerment framework or creating unequal conditions for telecommunications operators.
Go to TECHTRENDSKE.co.ke for more tech and business news from the African continent and across the world.
Follow us on WhatsApp, Telegram, Twitter, and Facebook, or subscribe to our weekly newsletter to ensure you don’t miss out on any future updates. Send tips to editorial@techtrendsmedia.co.ke

