Africa's telecoms operators are positioning themselves between satellite networks and customers

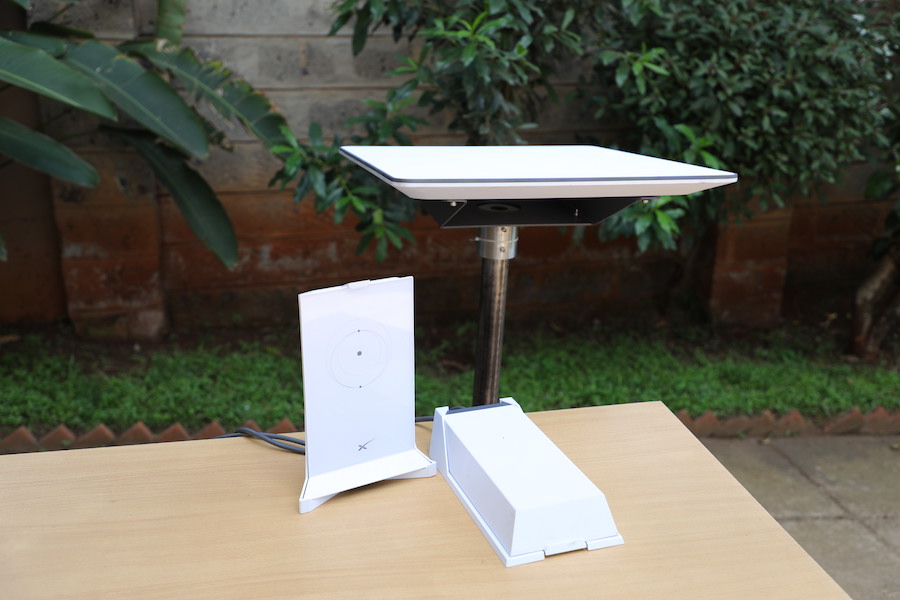
Satellite operators can own the infrastructure that connects remote communities to the internet, but they do not always control how customers access that service. Across Africa, licensing decisions, telecoms partnerships and wholesale arrangements are determining who can sell satellite connectivity, which businesses can participate and how users reach the network.
The commercial consequences extend beyond broadband subscriptions. An operator selling internet directly to households competes differently from one supplying capacity through a licensed internet service provider. A mobile network using satellites to reach phones presents another business model, with different requirements for spectrum, devices and network integration.
These distinctions are becoming important as Starlink expands its African footprint and Amazon Leo prepares to enter markets through local partners. The resulting market will depend partly on the satellite networks themselves, but also on the companies that control distribution, customer relationships and regulatory access.
Telecoms companies are building positions inside the satellite market
Satellite connectivity offers established telecoms operators a way to serve customers and locations that conventional terrestrial networks may struggle to reach economically. Partnerships also give satellite companies access to local sales channels, installation capabilities and existing customer bases.
Uganda provides an example of how these arrangements can develop. Paratus Uganda began commercial Starlink sales on 24 August 2026, following the satellite provider’s licence approval on 15 May. MTN Uganda subsequently announced its own reseller role, launching MTN Starlink for Business on 22 October at Libra International School in Zirobwe.
The two arrangements place local telecoms businesses between the satellite network and at least some of its customers. They also illustrate that one market can accommodate multiple distribution partners, although the competitive consequences depend on their commercial terms and the extent of any exclusivity.
The model has implications for other African operators. Vodacom, whose group includes Safaricom, has an Africa-wide Starlink mobile backhaul agreement. Starlink has also partnered with Mawingu to support approximately 450 digital hubs, schools and farmer cooperatives. These arrangements serve different purposes, but all show how satellite infrastructure can be incorporated into existing telecommunications and community-access operations.
The distinction matters because satellite connectivity does not always compete with terrestrial networks on a one-for-one basis. It can substitute for fixed broadband in some locations, extend mobile coverage in others, or supply backhaul capacity to a network operator. The effect on competition depends on which service is being sold and to whom.
South Africa shows how licensing can shape the route to customers
Regulation can determine which distribution models are available before a satellite company begins selling services.
Starlink has been unable to secure a South African licence under the country’s ownership requirements, which require 30% ownership by historically disadvantaged groups. SpaceX proposed an equity-equivalent package worth approximately R500 million, including free internet access for more than 5,000 rural schools. In May 2026, the Independent Communications Authority of South Africa said the law would need to change before it could recognise such an arrangement.
Amazon has pursued a different route. On 15 July, Amazon Leo signed an agreement with Herotel, a South African internet service provider. The service is to be sold under Herotel’s Evry brand, with Herotel handling sales, installation and customer support while Amazon supplies the satellite network. Commercial service was expected in 2027.
This arrangement gives Amazon a route into the market through an established local provider. It also places the customer-facing business in different hands from the company operating the satellite infrastructure.
That separation can make entry possible where direct licensing is difficult. Its effects on the market, however, depend on the agreement itself. Wholesale pricing, access to capacity, the ability of other ISPs to participate and any restrictions on competing services will help determine whether local distribution widens competition or concentrates it among a small group of partners.
The dispute in Senegal exposes the interests of incumbents
The commercial stakes are visible where a new satellite entrant challenges an established operator’s position.
Senegal licensed Starlink by ministerial order on 6 November 2025, and the service launched in February 2026. Sonatel challenged the entry. The ministry rejected the appeal in March, after which Senegal’s Supreme Court provisionally suspended Starlink’s licence on 7 September while it considers the case.
The legal dispute puts market access at the centre of the country’s satellite internet development. It also illustrates why licensing cannot be treated as a one-time administrative step. Decisions about entry can affect incumbent operators, alternative providers and customers who may benefit from additional connectivity options.
The case does not, by itself, establish whether satellite services should receive different treatment from terrestrial broadband. That question requires examining the relevant licensing rules, obligations and competitive effects. What it does show is that the arrival of a new network can become a contest over the terms under which a market is allowed to operate.
Satellite-to-phone services create a different competitive equation
Satellite internet is also expanding beyond dedicated terminals used at homes and businesses. Direct-to-phone services connect compatible mobile devices through satellite infrastructure, creating another route to coverage in places where conventional cellular networks are limited.
Airtel Congo launched Starlink Mobile in the Democratic Republic of the Congo on 14 August 2026. The service supports compatible LTE Android phones without requiring a separate satellite dish. Its initial capabilities include SMS and limited data services, including WhatsApp, at speeds below 1 Mbps. Voice calling is not supported.
Airtel Africa has said it plans to extend the service to all 14 of its African markets by the end of 2026. The company has also tested the technology in Kenya, Uganda and Madagascar.
This model differs from retail satellite broadband. Customers do not necessarily buy a satellite terminal or subscribe directly to a satellite provider. Their experience remains tied to a mobile operator’s service, supported devices and the technical and regulatory arrangements behind the connection.
That gives mobile operators a distinct role in the satellite market. They can incorporate satellite connectivity into their existing customer relationships, while satellite providers gain access to mobile users through a different distribution channel. The commercial arrangements and capabilities will vary by service, so direct-to-phone connectivity should not be treated as interchangeable with home broadband or satellite backhaul.
GSMA Intelligence’s third-quarter 2026 tracker found that 13% of mobile operators in sub-Saharan Africa had a satellite partnership, compared with 19% globally. The tracker forecast broad satellite-to-phone coverage around 2028 to 2029, pointing to a market that is still developing rather than one in which all mobile users can already expect seamless satellite connectivity.
Kenya’s market makes capacity and access part of the calculation
Kenya illustrates why the growth of satellite internet should be assessed alongside the practical limits of service delivery.
Communications Authority data showed 27,616 Starlink subscriptions by June 2026, up from 17,425 a year earlier, a 58.5% increase. Starlink accounted for approximately 99.7% of satellite internet subscriptions in the country, but satellite services still represented around 1% of the fixed internet market.
The numbers describe a provider with a strong position in a small segment of the wider broadband market. They also point to a distinction between gaining customers and meeting demand. Starlink users faced waiting lists in eight counties, while Ookla data showed median download speeds falling from about 47 Mbps to 34.55 Mbps by March 2026.
Satellite connectivity can help serve locations where fixed infrastructure is difficult or expensive to deploy. But subscriber growth alone does not establish whether capacity is keeping pace, whether prices are affordable to more households or whether users have a practical choice of providers.
The Communications Authority has published a draft Satellite Frequency Licensing Framework for 2026, with consultation scheduled to run until 6 November. The framework puts spectrum licensing on the regulatory agenda as satellite services become a more visible part of the country’s connectivity market.
Kenya is also considering the regulatory requirements for satellite-to-phone services. Airtel Kenya has completed a direct-to-cell pilot and is awaiting approval from the authority, according to earlier reporting by TechTrendsKE. Any rollout will involve a different set of operational questions from those surrounding conventional satellite broadband.
The terms of access will shape the market
The number of satellite partnerships is only one measure of how the market is developing. Their structure matters just as much.
An arrangement that allows several licensed ISPs to purchase capacity on comparable terms could extend the reach of a satellite network while preserving room for retail competition. A restrictive agreement could leave smaller providers dependent on a limited number of distributors. The available evidence from the different markets does not establish that one outcome is inevitable.
Regulators will need to consider whether partnership agreements restrict access to network capacity, how retail prices and service responsibilities are disclosed, and whether customers receive comparable protections regardless of how a connection is sold. For satellite-to-phone services, the questions also include compatibility, service limitations and the respective responsibilities of mobile and satellite operators.
Access for rural schools, community networks and smaller internet providers deserves attention alongside commercial rollout. Partnerships can make these groups easier to reach, as the Mawingu arrangement demonstrates, but the existence of a programme does not establish its long-term affordability or the conditions under which others can participate.
Satellite companies bring infrastructure that can reach beyond the practical limits of terrestrial networks. Local telecoms operators bring distribution, customer relationships and knowledge of domestic markets. Governments determine the rules under which those assets can be combined.
The outcome for African consumers will depend on how those roles are allocated. More satellite capacity may expand the range of available connections, but the structure of the market will determine who can sell them, which providers can compete and how much choice customers ultimately receive.
Go to TECHTRENDSKE.co.ke for more tech and business news from the African continent and across the world.
Follow us on WhatsApp, Telegram, Twitter, and Facebook, or subscribe to our weekly newsletter to ensure you don’t miss out on any future updates. Send tips to info@techtrendsmedia.co.ke