Jubilee teams up with seven insurtechs to develop affordable insurance for underserved Kenyans

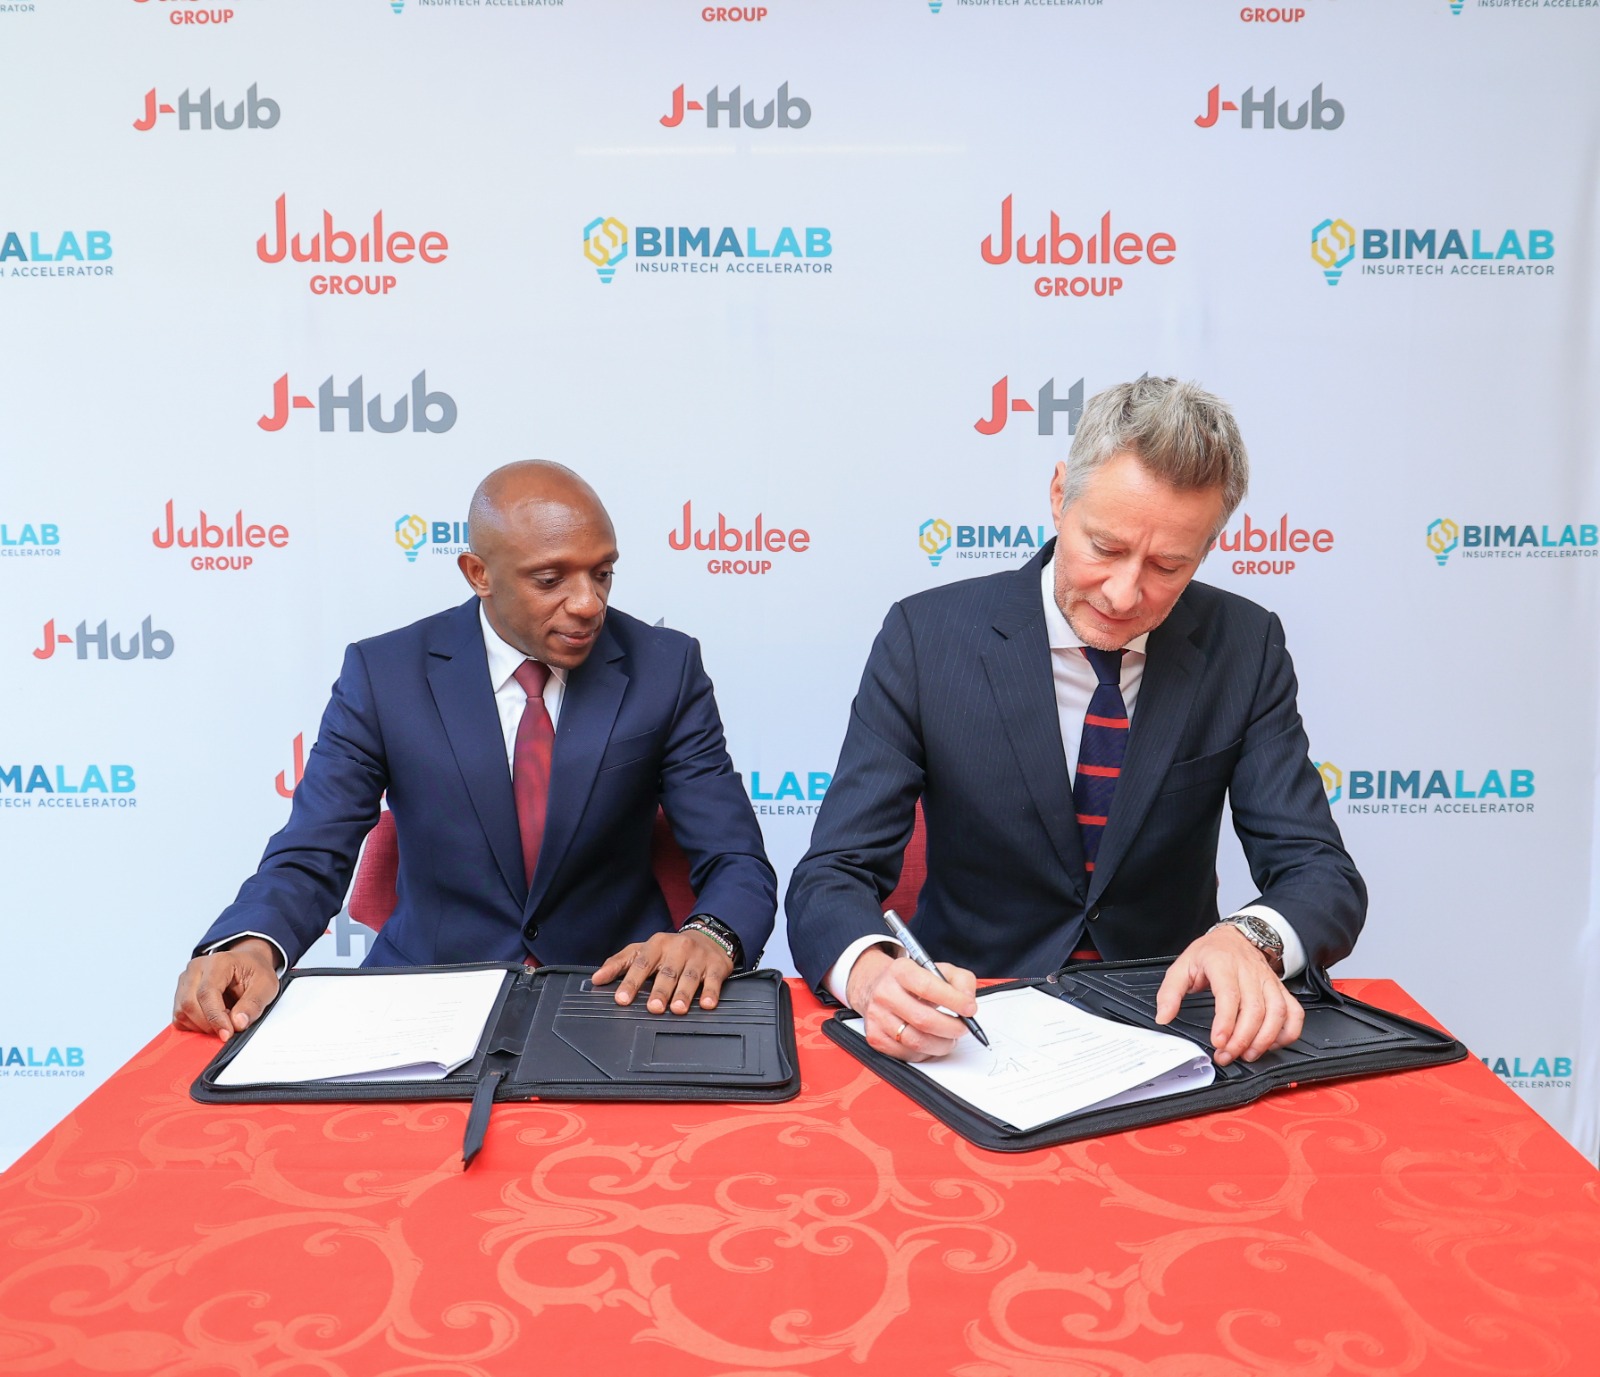
Jubilee Group and FSD Africa are working with seven insurtech companies to develop and test affordable insurance products for underserved Kenyans, including small and medium-sized enterprises (SMEs), informal sector workers, farmers and low-income households.
The partnership will move through an eight-week product co-creation process with Jubilee before joint pilot programmes begin in Kenya in November 2026. The focus is on more than developing new policies. The companies will also examine how insurance can be distributed through channels customers already use, how protection can be built around SME ecosystems, and how insurance can connect with health and wellness services.
The seven participating companies are Dukatech Solutions, Aura Insure Technologies, Inclusivity Solutions, DPE, Fiinovate, Agrails and Ibisa Network. They were selected through a competitive process from the BimaLab Africa Insurtech Accelerator alumni network.
The programme arrives as insurers in Kenya face a familiar problem: digital channels have expanded, but insurance uptake remains low. The industry is increasingly looking at technology not simply to put existing products online, but to reduce the cost and friction involved in reaching customers who have historically been difficult to serve.
The distribution problem behind Kenya’s insurance gap
Jubilee’s latest initiative builds on a broader shift already taking place in the Kenyan insurance market.
In July, Jubilee Health Insurance partnered with bolttech to embed health insurance into digital platforms used by banks, retailers, petrol stations, buy-now-pay-later providers and digital marketplaces. The model allows customers to encounter insurance while completing other transactions rather than starting a separate insurance-buying journey. The underlying technology supports onboarding, policy administration, premium collection and claims processing through APIs.
That experience provides useful context for the new programme.
Dukatech Solutions, for example, will use its Shopokoa platform and existing network of informal sector workers to explore bundled and embedded insurance. Aura Insure Technologies and Inclusivity Solutions bring digital underwriting, distribution and embedded insurance capabilities.
The common thread is distribution.
For a small trader, informal worker or microbusiness owner, insurance may not rank high enough on the list of daily priorities to justify a separate sales process. Embedding protection into an existing financial, commercial or digital relationship can reduce that friction.
The question for Jubilee and its partners is whether those models can make insurance sufficiently simple and affordable to become relevant to customers who have traditionally remained outside the formal insurance market.
SMEs are becoming a bigger insurance opportunity
SMEs are an important part of that equation.
TechTrends reported in August that NCBA Insurance was expanding its business insurance offering for Kenyan SMEs, with premiums starting from KSh15,000 and cover of up to KSh1 billion depending on the business and level of protection. Research cited by the insurer indicated that about 53% of small and growing businesses surveyed in Nairobi did not have active insurance cover.
The problem is not confined to general business risks.
In September, TechTrends reported on Equity’s SME Health Cover, which targets small businesses as well as SACCOs, chamas, schools, churches, staff groups and other organisations that can struggle to fit conventional corporate insurance models.
Sanlam Allianz has also identified SME business as a growth opportunity, with its Kenyan operation highlighting the need for simpler and more relevant insurance solutions for enterprises.
Jubilee’s partnership fits into this wider movement.
Fiinovate will explore credit-linked insurance solutions aimed at SMEs and borrowers, potentially connecting insurance to the same financial relationships through which businesses access credit.
That creates a different proposition from selling a standalone policy. Insurance can become part of a broader financial resilience package, protecting a borrower or business against events that could otherwise interrupt income and make repayment difficult.
The seven companies bring different pieces of the technology stack
The participating insurtechs have been assigned different areas of focus.
Dukatech Solutions will use Shopokoa and its informal-sector network to explore bundled and embedded insurance. Aura Insure Technologies and Inclusivity Solutions will contribute digital underwriting, distribution and embedded insurance technologies.
DPE will work on health and wellness engagement through SMS, WhatsApp and voice platforms. Its role points to another practical issue in insurance: reaching customers does not end when a policy is sold. Customers need to understand their cover, remain engaged with it and know how to access services when they need them.
Fiinovate will examine credit-linked insurance for SMEs and borrowers, while Agrails will bring climate intelligence and parametric technology to the programme.
Ibisa Network will use satellite data and AI-driven analytics to explore parametric protection for farmers and renewable energy operators.
The combination is significant because it covers several parts of the insurance value chain, from underwriting and distribution to customer engagement and risk assessment.
It also gives Jubilee an opportunity to compare different approaches with real customers rather than evaluating the technologies only in an accelerator environment.
Technology has to improve the economics of insurance
The affordability question is more complicated than simply lowering premiums.
Kenya’s insurance industry has been under pressure to improve efficiency as it competes for customers while dealing with fraud, claims costs, distribution expenses and relatively low penetration.
TechTrends reported in June that insurers are increasingly using artificial intelligence for fraud detection, underwriting, claims processing and customer engagement. Industry executives, however, stressed that technology investments need to produce measurable improvements in efficiency, customer retention and business performance.
That issue is particularly relevant to the Jubilee/FSD Africa programme.
If an insurtech can reduce the cost of acquiring a customer, improve risk assessment, automate part of the administration process or reduce claims leakage, the insurer has more room to offer products at prices that underserved customers can afford.
The alternative is simply cutting premiums without changing the economics underneath them.
That approach has its own risks. TechTrends’ September coverage of Old Mutual’s pricing strategy highlighted the tension between competitive premiums and sustainable underwriting. The insurer has been using tighter underwriting, fraud controls and AI-enabled processes to improve efficiency rather than relying solely on price competition.
For Jubilee and the seven insurtechs, the challenge is therefore to find models where affordability comes from a more efficient way of designing, distributing and servicing insurance.
Climate risk creates another opening for insurtech
Agriculture provides one of the clearest examples.
Traditional insurance can be difficult to administer when risks are geographically dispersed and losses depend on weather conditions. Assessing individual claims across large numbers of farms can also make products expensive to operate.
Agrails’ climate intelligence and parametric technology offers another approach.
Parametric insurance uses an agreed trigger, such as a specified rainfall level or other measurable weather condition, to determine whether a payout is activated. Satellite data and other forms of remote sensing can provide information across areas where physical claims assessment would be costly or impractical.
Ibisa Network’s use of satellite data and AI-driven analytics will similarly explore parametric protection for farmers and renewable energy operators.
That makes the partnership relevant beyond traditional health and business insurance. It puts technology at the centre of efforts to create protection for economic activities that are particularly exposed to climate-related disruption.
From accelerator ideas to real customers
The programme’s connection to the BimaLab Africa Insurtech Accelerator is also important.
Africa’s insurtech sector has produced a growing number of startups focused on digital distribution, data, payments and new forms of risk protection. But the industry is increasingly being judged on whether those technologies can translate into sustainable businesses.
TechTrends reported in September that African insurtech is facing greater pressure to move from product development and fundraising toward revenue generation, customer acquisition, geographic expansion and commercial sustainability.
The Jubilee/FSD Africa programme puts that question into a practical setting.
The eight-week co-creation process gives the companies an opportunity to adapt their technologies around an established insurer and specific customer segments. The pilots then provide a route to see which solutions work outside an accelerator environment.
For Jubilee, the exercise also creates a way to compare different approaches before committing resources to wider deployment.
Products and distribution models that demonstrate potential during the pilots could eventually be expanded into other East African markets.
Health, credit and insurance are beginning to converge
The programme’s health and wellness component adds another layer to this shift.
DPE will explore engagement through SMS, WhatsApp and voice platforms, while the broader programme will look at ways of connecting insurance customers to health and care services.
This reflects a wider movement in financial services where insurance is increasingly being positioned alongside payments, credit, healthcare and other services rather than as an entirely separate product.
Jubilee’s bolttech partnership illustrates the same direction. The insurer has been experimenting with placing health protection inside financial and commercial journeys, while the new programme extends that approach to additional customer groups and technologies.
For customers, the practical benefit is potentially straightforward. A financial service, business platform or healthcare interaction that already has their attention can become a route into insurance without requiring them to navigate a separate sales channel.
The pilots will have to prove more than digital adoption
There is a temptation in technology programmes to measure success by the number of customers onboarded or policies sold.
For this initiative, those numbers will tell only part of the story.
The more important questions will be whether customers understand the products, whether premiums remain affordable, whether claims can be processed efficiently and whether the models work commercially for both Jubilee and its distribution partners.
Data governance will also become increasingly important as the programme introduces digital underwriting, AI analytics, satellite data and automated customer engagement.
Technology can reduce friction, but it cannot by itself solve the trust problem that has constrained insurance adoption. Customers still need confidence that the product is relevant, the terms are understandable and a valid claim will be paid when a loss occurs.
That makes the pilots a useful test of both technology and insurance design.
A test of how Kenya can widen insurance access
Jubilee and FSD Africa are effectively bringing together different pieces of Kenya’s insurtech ecosystem to address a problem that has resisted conventional distribution.
The seven companies are approaching that problem from different directions: informal-sector networks, embedded insurance, digital underwriting, customer engagement, credit, climate intelligence, satellite data and AI.
The commercial question is whether those technologies can do more than make insurance digital.
They need to make it easier to reach, easier to understand, affordable to maintain and viable for the insurer to provide.
That is the more consequential part of the November pilots. If the models can demonstrate that technology can improve both access and the economics of serving underserved customers, Jubilee will have a clearer route to scale them in Kenya and potentially across East Africa.
Real ESG impact doesn’t happen in panels alone, it happens in the rooms where financiers, operators, and policymakers actually align. Our GreenShift Forum 2026 cuts the noise, bringing together the people rewiring Africa’s sustainability and energy frameworks for one focused day in Nairobi. Secure your seat.
Go to TECHTRENDSKE.co.ke for more tech and business news from the African continent and across the world.
Follow us on WhatsApp, Telegram, Twitter, and Facebook, or subscribe to our weekly newsletter to ensure you don’t miss out on any future updates. Send tips to info@techtrendsmedia.co.ke