Saccos gain ground as more Kenyan farmers borrow to finance production

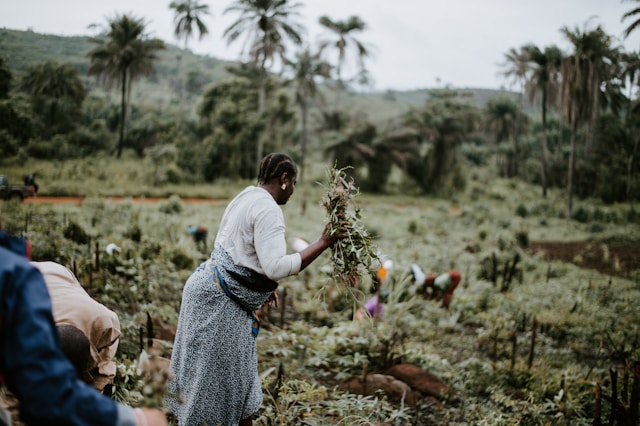
Kenyan farmers are turning more frequently to Saccos and commercial banks for farm credit, as the proportion borrowing to finance agricultural activities rose between July and September 2026, according to a Central Bank of Kenya (CBK) survey. Saccos recorded the largest increase among the reported sources of borrowing, with their share rising to 32% in September from 17% in July. Commercial bank borrowing also increased, reaching 29% from 21% over the same period.
The changes coincided with a rise in the proportion of sampled farmers reporting that they had borrowed to finance agricultural activities, from 34% in July to 45% in September. Meanwhile, the share borrowing from family and friends fell to 29% from 38%, reversing the position recorded in July when personal networks were the leading reported source of farm credit. The figures point to a changing mix of financing sources as farmers meet the costs of running their farms.
Kenyan farmers rely more on Saccos and banks
Saccos recorded a 15-percentage-point increase in their share of reported borrowing over the two-month period, compared with an eight-point rise for commercial banks. Borrowing through informal savings and credit groups also increased, reaching 22% in September from 16% in July. Digital borrowing moved in the opposite direction, with the proportion reporting digital loans falling to 13% from 16%.
The changes suggest that farmers are drawing on several forms of credit to finance agricultural activities, even as Saccos and banks account for a greater share of reported borrowing. The survey was conducted between September 21 and 25 among 466 respondents drawn from selected farms and food markets.
Saccos occupy a substantial position in Kenya’s financial system. By the end of 2024, regulated Saccos held KSh1.08 trillion in assets and had extended KSh845.11 billion in gross loans, according to figures from the Sacco Societies Regulatory Authority. Their established role in savings and lending makes them an important part of the financial landscape in which farmers seek working capital.
Commercial banks are also a source of financing for agricultural operations, with their lending activity taking place against a backdrop of changes in overall credit conditions. The CBK reported an average commercial bank lending rate of 14.40% in September 2026, compared with 14.34% in August and 14.39% in July. The Central Bank Rate stood at 8.75% following the Monetary Policy Committee’s October decision to maintain it at that level.
Farm inputs and labour drive credit demand
The uses of agricultural loans offer a clearer picture of why farmers need financing. The CBK reported that 91% of respondents using agricultural credit had borrowed to purchase farm inputs in September, up from 81% in July. The share using agricultural loans to meet labour costs rose to 60% from 49% over the same period.
Inputs such as seeds, fertiliser and pesticides must often be purchased before a farmer receives income from a harvest. Labour costs follow a similar cycle, as workers need to be paid while cultivation, weeding, harvesting and other farm activities are under way. Credit can help farmers cover these expenses before their produce reaches the market and generates cash.
The figures also underline the importance of working capital in agricultural production. Farmers who lack sufficient cash at the start of a planting season may need external financing to purchase inputs or hire workers, while their ability to repay depends partly on the income generated by the resulting harvest.
The higher proportion of respondents reporting loans for inputs and labour points to the central role these expenses play in farm financing. For lenders, this makes the timing of agricultural cash flows important, since the expenditure required to produce a crop comes before the revenue earned from selling it.
Lending costs and agricultural financing
The increase in reported bank borrowing comes as average commercial lending rates remain below the levels recorded at the beginning of the year. The CBK’s September rate of 14.40% was lower than the 14.81% recorded in January, although the average was broadly stable between July and September.
These rates cover commercial bank lending across the economy rather than agricultural loans alone. Farmers’ financing decisions also depend on whether they qualify for credit, the amount available, repayment arrangements and the timing of their production expenses.
The changing distribution of borrowing sources is relevant to financial institutions seeking to serve agricultural customers. Saccos, banks and informal credit networks provide different channels through which farmers can access funds, while the costs and terms of borrowing influence how well those funds match seasonal production needs.
Weather risks complicate loan repayment
Farm credit carries risks tied to the conditions under which farmers produce and sell their crops. The CBK survey found that 76% of sampled farmers relied mainly on rain-fed agriculture, leaving their production exposed to rainfall patterns and other weather conditions.
Weather also affects the wider food market. In the same survey, 97% of respondents identified weather conditions as a factor affecting retail prices, while 92% cited transport costs and 80% pointed to input prices. These pressures can affect both the cost of production and the income farmers receive when they sell their produce.
For a farmer who has borrowed to buy fertiliser, seeds or pesticides and pay workers, a poor harvest can reduce the money available for repayment. Transport expenses and changes in selling prices can also influence how much remains after the crop reaches the market. As Saccos and banks account for a larger share of reported farm borrowing, the relationship between seasonal production, farm income and repayment capacity remains central to agricultural finance in Kenya.
Go to TECHTRENDSKE.co.ke for more tech and business news from the African continent and across the world.
Follow us on WhatsApp, Telegram, Twitter, and Facebook, or subscribe to our weekly newsletter to ensure you don’t miss out on any future updates. Send tips to editorial@techtrendsmedia.co.ke