Kenya’s REIT market expands as industry leaders call for rules that accommodate modern infrastructure

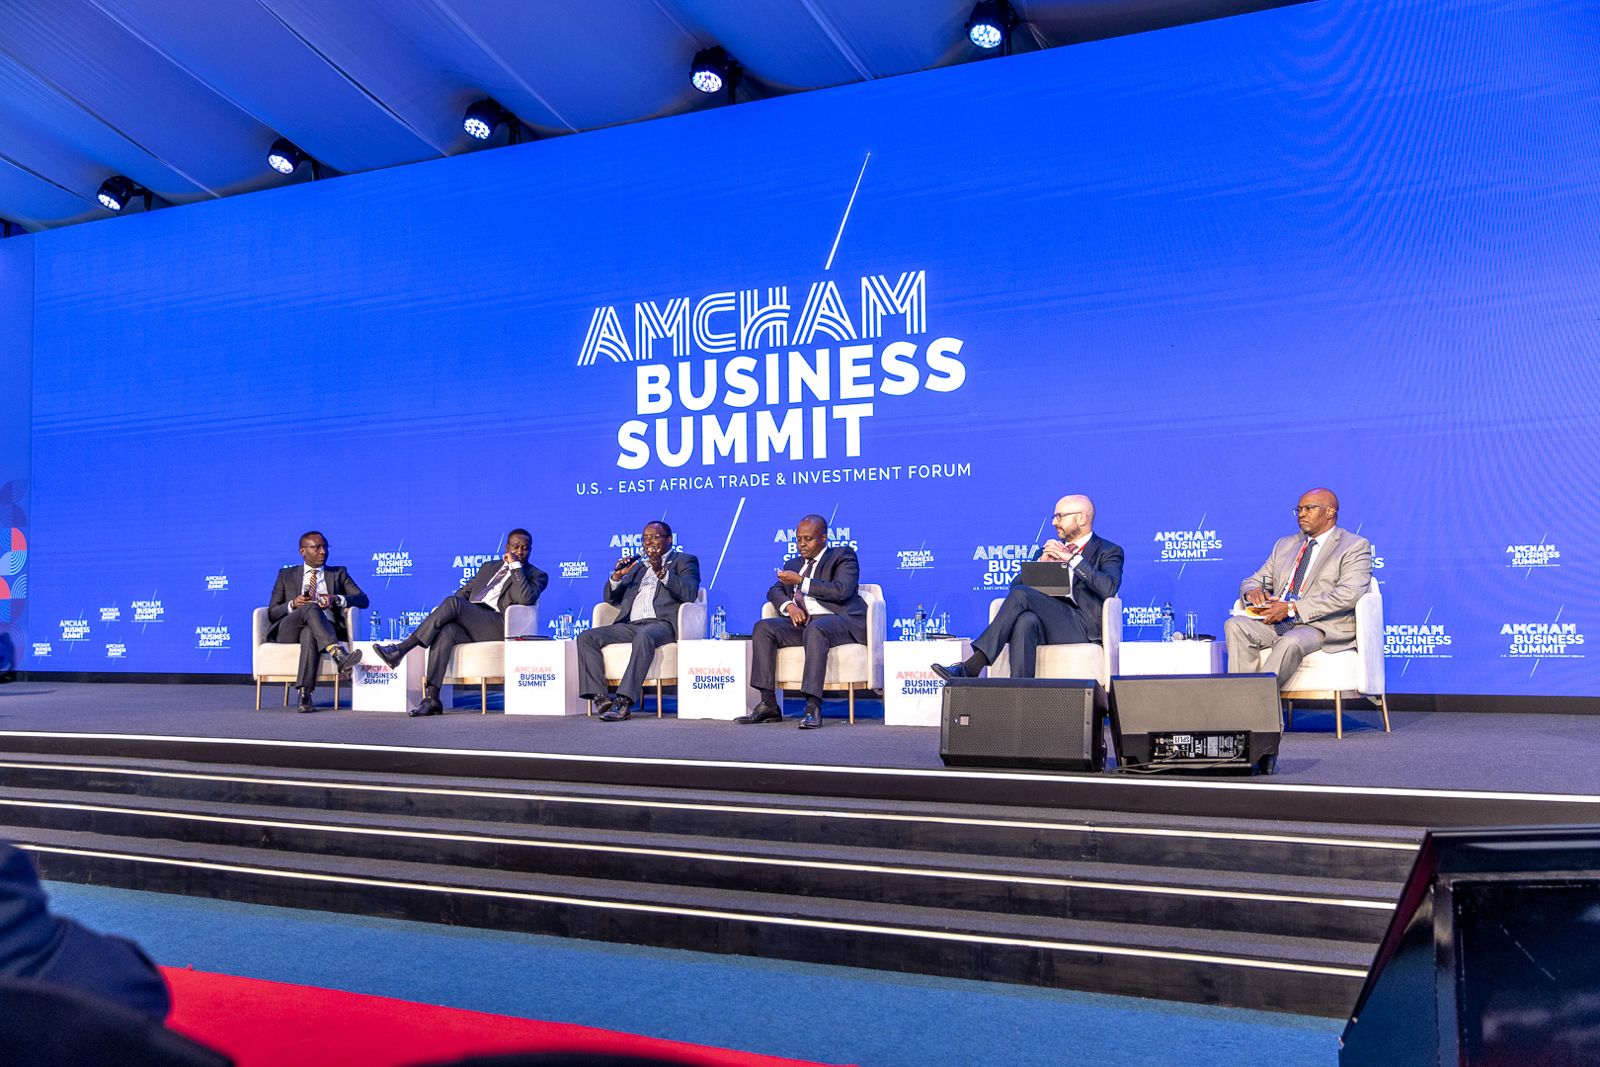
Kenya’s Real Estate Investment Trusts (REITs) market is facing calls for regulatory reform as industry participants argue that the framework should accommodate a broader range of assets and investment structures.
Speaking at the AmCham Kenya 2026 Business Summit, Peter Waiyaki, Partner at Mboya Wangong’u & Waiyaki Advocates, proposed changes that would widen the definition of eligible real estate, bring infrastructure assets such as telecommunications towers and data centres into consideration, and revisit the rules governing qualifying income and public shareholding.
The market has grown since the launch of ILAM Fahari I-REIT in October 2015, Kenya’s first REIT instrument. It now includes income and development structures, alongside newer US-dollar-denominated instruments such as the ALP D-REIT, ALP I-REIT and TRIFIC Green USD I-REIT. Waiyaki’s argument is that the rules governing these vehicles should reflect the assets and revenue models that investors are seeking as Kenya’s investment market develops.
The market has expanded beyond its early foundations
Kenya’s REIT market remains relatively small, but its range of investment structures has widened. A May 2024 report on NCBA’s entry into REIT trustee services identified four existing REITs at the time: ILAM Fahari Income REIT, Acorn Development REIT, Acorn Income REIT and Lapfund Imara Income REIT. Subsequent instruments, including TRIFIC’s US-dollar-denominated offering, point to a market adding new forms of exposure to income-generating property.
TRIFIC provides a recent example of that diversification. The TRIFIC Green USD I-REIT targeted approximately US$30 million through a public offer backed by the North Tower office development at the Two Rivers Special Economic Zone. The property’s tenant base includes businesses in outsourcing, technology, consulting and digital services, while the vehicle’s dollar denomination offers investors exposure to rental income in a foreign currency.
The offer closed with approximately US$30.82 million raised against a US$29.83 million target, representing 103.3% subscription. Including the sponsor’s contribution of the underlying property, the vehicle’s total value was reported at nearly US$37.3 million. The result demonstrates demand for specialised property investment products, although initial fundraising should be distinguished from the secondary-market liquidity that develops after listing.
Tax incentives have also helped make REIT structures attractive to sponsors and investors. Their precise treatment depends on the applicable tax provisions and the structure involved, but the policy rationale is to reduce friction around property investment vehicles and make it easier to pool capital into income-generating assets. Any further reform, however, will need to consider both the incentives available to REITs and the safeguards intended to preserve their investment character.
Why infrastructure assets are part of the debate
Waiyaki argued that the definition of real estate under Kenya’s regulatory framework should move beyond a traditional understanding of property. In particular, he identified telco towers, fibre facilities and data centres as assets that should be considered when determining what may qualify for REIT treatment.
The proposal reflects the changing composition of the built environment. A modern data centre, for example, combines land and buildings with specialised power, cooling and computing infrastructure. Telecommunications towers and fibre networks also require substantial upfront investment and can generate recurring revenue through leases, capacity agreements or long-term service arrangements.
These characteristics make such assets relevant to investors seeking predictable, long-duration income. They also create a regulatory challenge because infrastructure assets can sit between property ownership and operating businesses. A REIT framework must determine which assets qualify, how they are valued, how operating risks are handled and whether the revenue they generate meets the requirements for qualifying income.
The question is therefore broader than whether a data centre should be classified as real estate in the ordinary sense. It is whether the regulatory framework can recognise asset-backed infrastructure businesses whose economics may resemble those of income-producing property while retaining rules that distinguish investment vehicles from ordinary operating companies.
The wider infrastructure-financing debate in Kenya provides useful context. Proposals around the National Infrastructure Fund have focused on using pension funds, banks and other institutional investors to finance commercially viable infrastructure through structured investment vehicles. A proposed infrastructure development fund, potentially listed on the Nairobi Securities Exchange, illustrates the appeal of giving investors exposure to diversified infrastructure portfolios rather than requiring them to finance individual projects directly.
That does not mean infrastructure assets are already eligible for REIT treatment, or that every infrastructure company should qualify. It does show why the question of eligible assets is becoming more relevant as Kenya seeks ways to connect domestic savings with long-term investment opportunities.
Lease and income rules could limit new structures
Waiyaki also called for a review of the lease requirements and the definition of income used to determine whether an instrument qualifies as a REIT.
Traditional property REITs generally rely on rental income from real estate assets. Infrastructure assets, however, may earn revenue through a mixture of leases, licences, capacity agreements, concessions and service contracts. A framework built around conventional landlord-and-tenant arrangements may not always accommodate these models without additional interpretation or amendments.
The distinction is important because qualifying-income rules help preserve the character of a REIT. They are intended to ensure that the vehicle is primarily an investment structure holding income-producing assets, rather than an operating company using the REIT label. Any reform would therefore need to recognise a wider range of predictable, asset-backed revenue arrangements without removing the safeguards that make the structure meaningful to investors.
A more flexible approach could give sponsors room to develop vehicles around infrastructure assets while allowing regulators to assess the nature of the underlying income, the level of operational exposure and the risks transferred to investors. The details would matter: broadening eligibility without clarifying the treatment of revenue, maintenance obligations and valuation could create uncertainty rather than resolve it.
Free-float requirements raise a market-depth question
Another proposal concerns Kenya’s mandatory 25% free-float requirement. Waiyaki argued that the threshold may be difficult to meet for a sizeable REIT in a market where public-investor depth remains limited. He suggested that a free float of 10% or 5% could be a more realistic expectation for some large instruments.
Free float refers to the proportion of shares available for public trading rather than held by controlling shareholders or other restricted holders. For a REIT sponsor, the requirement can affect how much ownership must be distributed to the public, how much capital must be raised through a public offer and how the vehicle is structured before listing.
The argument for a lower threshold is that a large REIT may require substantial capital, while the available pool of investors able to absorb a sizeable public offer may be limited. A lower free float could make it easier to bring larger assets or portfolios to market without requiring an offering that exceeds realistic demand.
There is a trade-off, however. A smaller public float can reduce the number of shares available for trading, potentially affecting liquidity, price discovery and investor participation. The question for policymakers is whether the existing threshold is appropriately calibrated to Kenya’s market conditions, and whether flexibility could be introduced without undermining the public-market role of listed REITs.
The distinction between fundraising and liquidity is particularly relevant in the case of TRIFIC. Its oversubscribed offer provides evidence of demand for the initial transaction, but that result alone does not establish how actively the instrument will trade or how efficiently investors will be able to enter and exit their positions. Those are separate measures of market development.
Reform could widen the pool of investable assets
The proposals come as Kenya’s broader investment market is becoming more diversified. Collective investment scheme assets reached approximately KSh948.7 billion by June 2026, while foreign-currency-denominated fund assets rose to KSh110.5 billion. The figures cover a much wider universe than REITs, but they illustrate the growing importance of specialised investment products and foreign-currency exposure within the financial system.
REITs occupy a particular place in that landscape because they can connect investors to physical assets that would otherwise require substantial capital and specialist management. They also offer a potential route for institutional investors, including pension funds, to gain exposure to real estate and infrastructure through pooled structures.
For Kenya, the policy opportunity lies in making the market broad enough to accommodate viable assets while preserving investor protections. That could involve clarifying the treatment of infrastructure, reviewing the income and lease rules, and examining whether free-float requirements can be adjusted to reflect the realities of the local market.
Waiyaki’s proposals remain calls for reform rather than adopted changes to the regulatory framework. Their significance is that they place the future of Kenya’s REIT market within a wider discussion about capital mobilisation, infrastructure financing and the ability of the country’s investment markets to support assets that do not fit neatly into traditional categories.
Real ESG impact doesn’t happen in panels alone, it happens in the rooms where financiers, operators, and policymakers actually align. Our GreenShift Forum 2026 cuts the noise, bringing together the people rewiring Africa’s sustainability and energy frameworks for one focused day in Nairobi. Secure your seat.
Go to TECHTRENDSKE.co.ke for more tech and business news from the African continent and across the world.
Follow us on WhatsApp, Telegram, Twitter, and Facebook, or subscribe to our weekly newsletter to ensure you don’t miss out on any future updates. Send tips to editorial@techtrendsmedia.co.ke