Quickmart ends founder-linked contracts after hundreds of millions in payments during IPO

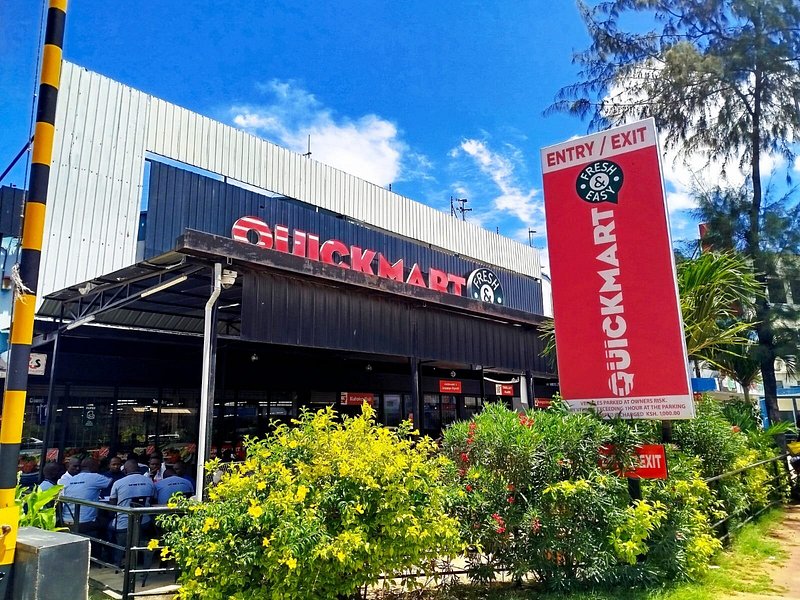
Quickmart terminated several founder-linked consultancy and management agreements in July 2026 after disclosing hundreds of millions of shillings in payments to related parties, according to the supermarket chain’s IPO disclosures.
The Quickmart related-party contracts covered management services, property sourcing, construction oversight, lease negotiations, supplier engagement and business expansion advice. While the agreements have ended, 18 store locations remain leased from parties linked to the retailer’s founders, directors or the founder of Tumaini Self Service, which merged with Quickmart.
The disclosures come as Quickmart’s initial public offering remains open, with the share offer scheduled to close on 30 October 2026 and trading expected to begin on the Nairobi Securities Exchange (NSE) in November, subject to the official timetable. They provide investors with a closer look at the commercial relationships behind the retailer’s operations as they assess its disclosures during the offer period. The available information does not establish that the arrangements were improper or that the IPO prompted the terminations.
Quickmart disclosed hundreds of millions in related-party payments
Quickmart paid KSh208.4 million in management fees to its intermediate and ultimate parent companies, Sokoni Retail Kenya Limited and Sokoni Holdings Limited, in the 2025 financial year. That was an increase from KSh141.4 million in FY2024, representing growth of approximately 47.4%.

Separate payments covered property and expansion services. Basic Land Investment Limited received KSh268.7 million in FY2025 and KSh99.4 million in the first half of 2026 for services including property sourcing, construction, lease negotiations, landlord relations and commercial negotiations. Resource Business Investments Limited received KSh161 million in FY2025 and KSh84.9 million in the first half of 2026 for expansion advice, supplier negotiations, asset and site selection, and market advisory services.
The three FY2025 payment categories total KSh638.1 million. This is a subtotal covering the disclosed management fees and payments to the two service providers, not a verified total for every related-party arrangement. The payments also relate to different services, so their combined value does not establish that Quickmart paid multiple firms for identical work.
The information memorandum also identifies consultancy agreements with Acres Advisors Limited, WLL Valued Added Limited, Mondin Consulting Limited and Elijah Okello. Their respective mandates included management and staff advice, retail operations, environmental and social compliance, human resources, other consultancy services, and site planning, fit-out and community relations. Okello holds a 4.4% interest in Sokoni Retail Kenya Limited.
Some of the service descriptions overlap, particularly in management advice, commercial negotiations and expansion. This raises questions about how responsibilities were divided between providers and how the company assessed the value of each engagement. However, establishing whether work was duplicated would require more detailed information on contractual scopes, services delivered and billing arrangements.
Consultancy and management agreements ended in July
The disclosed terminations took effect in July 2026, approximately three months before the scheduled close of the IPO offer. The timing is relevant to investors reviewing the information memorandum, but the available disclosures do not establish that the contracts were terminated because of the listing or following a regulatory directive.
The arrangements covered activities central to operating and expanding a supermarket chain. Property sourcing, construction oversight, lease negotiations, supplier relationships and site selection can influence the cost of opening new stores and the economics of existing locations. Payments for these services are not inherently evidence of a conflict, particularly where a business has grown through relationships with founders and associated companies, but the terms and oversight of related-party transactions remain relevant to investors assessing how the company is managed.
Quickmart chief financial officer Simon Macharia has described the company’s wider governance processes, including monthly board meetings, weekly executive committee meetings and daily reporting of sales and cash flows. He has also spoken about the need for financial decisions to be based on commercial considerations rather than personal relationships.
Those statements outline management’s account of the retailer’s control environment. They do not independently establish how each terminated agreement was approved, whether fees were benchmarked against independent providers, or what role non-conflicted directors played in reviewing the arrangements. Regular financial reporting and board meetings are relevant to corporate governance, but they do not by themselves answer questions about the review of individual transactions involving related parties.
Eighteen store leases remain linked to related parties
Although the consultancy and management agreements have ended, Quickmart continues to lease 18 store locations from related parties controlled by its founders or directors, or by the founder of Tumaini Self Service. The information memorandum says the leases are on arm’s-length terms and contain no unusual provisions.
These continuing property relationships matter because Quickmart operates through leased premises. In his interview, Macharia said the retailer does not own the land and buildings used for its stores and generally enters into leases lasting between 10 and 12 years. He also described the use of bank guarantees for lease deposits.
The leases should therefore be considered separately from the terminated service agreements. Ending consultancy mandates does not remove the commercial relationship associated with a leased property, while the existence of a related-party landlord does not itself establish that rents are above market rates. Assessing the arrangements would require details such as rental levels, independent market comparisons, lease duration, renewal provisions and the process used to approve transactions involving connected parties.
Quickmart’s statement that the leases are on arm’s-length terms represents the company’s disclosed position. The available information does not independently establish how each lease was valued or reviewed.
Governance disclosures come under scrutiny during IPO
Quickmart’s IPO involves the sale of two billion existing shares at KSh7.50 each, giving the offer a gross value of KSh15 billion and implying an equity valuation of KSh30 billion. Because this is a secondary share sale by existing shareholders, the proceeds are intended for the sellers rather than being raised directly by Quickmart as new capital.
The retailer reported FY2025 revenue of KSh50.4 billion, compared with KSh46.7 billion in FY2024, and net profit of approximately KSh1.5 billion, up from KSh1.1 billion. With 72 stores and plans for further expansion, the management of property costs, supplier relationships and expansion spending remains relevant to its financial performance and growth plans.
The information memorandum acknowledges that related-party arrangements may give rise to actual or perceived conflicts of interest and that their terms could differ from those available from independent third parties. Separately, it states that the directors, senior management and experts had no known conflicts that could materially affect the offer shares as of the document’s date. These disclosures address different issues and should be read in that context.
For prospective investors, the questions concern how related-party transactions are identified, approved and priced, and whether those processes can be independently assessed. The termination of several service agreements documents a change in Quickmart’s commercial arrangements, while the continuing leases show that some related-party relationships remain part of its operating structure.
The disclosures do not establish misconduct. They do, however, give investors specific payment figures, contract changes and continuing property relationships to consider as Quickmart’s IPO offer progresses towards its scheduled close on 30 October.
Go to TECHTRENDSKE.co.ke for more tech and business news from the African continent and across the world.
Follow us on WhatsApp, Telegram, Twitter, and Facebook, or subscribe to our weekly newsletter to ensure you don’t miss out on any future updates. Send tips to info@techtrendsmedia.co.ke