Why African fintech companies are moving deeper into the services businesses need to operate

African fintech companies are expanding beyond payment acceptance as they seek to provide the financial and operational services businesses need to manage their daily activities. The move towards African fintech business services was a central discussion at Moonshot 2026, where executives from Mastercard, Remita and OPay argued that merchants need more than systems that process transactions.
The executives said businesses also require cash-flow management, customer insights, fraud reduction, reliable support and staff training. Paystack chief executive Shola Akinlade similarly placed wider business infrastructure at the centre of the company’s next growth phase, describing an ambition to address financial needs that extend beyond payment acceptance.
The discussions reflect a broader commercial opportunity for providers that already have relationships with merchants. A company processing payments can build on those transactions to offer financing, business tools and other services, giving merchants more reasons to remain within its platform.
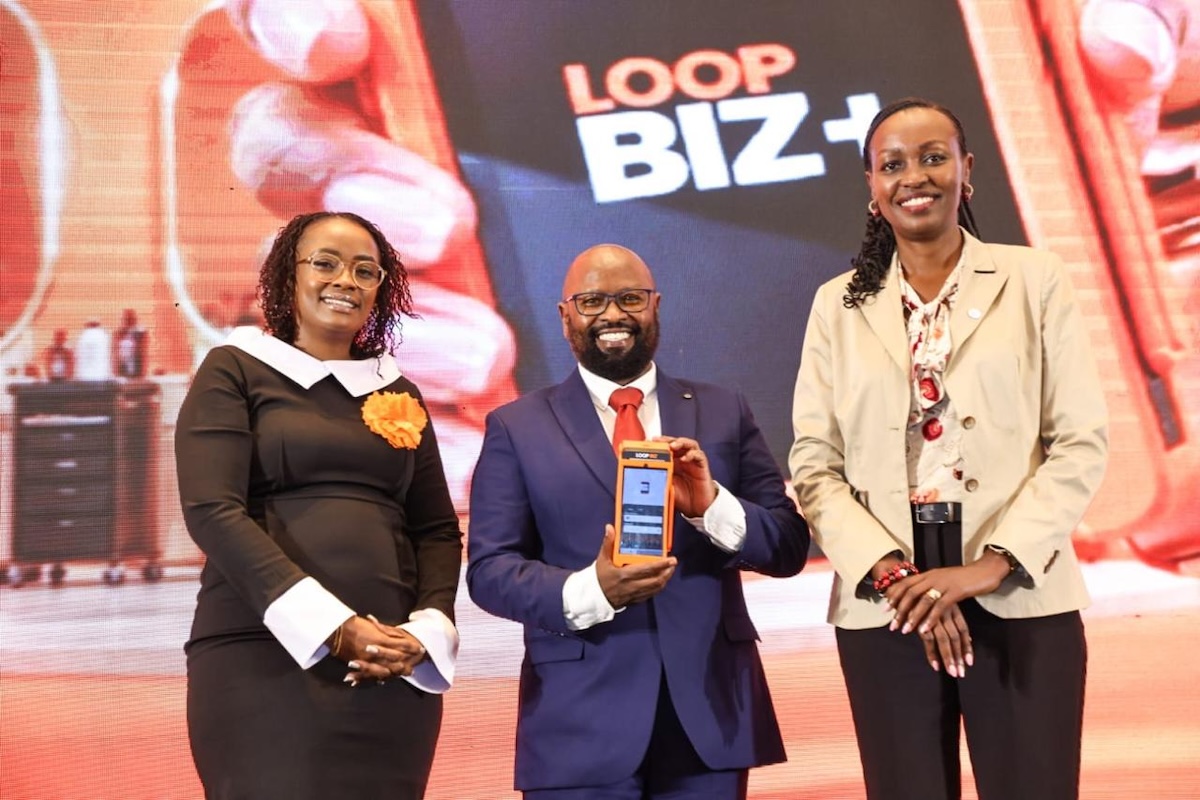
Kenya provides a useful example of how that model is taking shape. NCBA’s LOOP DFS launched LOOP BIZ+, a merchant platform that brings together payment acceptance, working-capital loans, supplier credit and AI-powered inventory management. Its point-of-sale offering accepts card, contactless and mobile money payments, while merchant transaction histories can help determine eligibility for credit.
The product places several business functions within one platform. A merchant can receive payments, access financing and manage inventory through services connected to the same commercial relationship. That model also gives the provider a closer view of the merchant’s business activity, which can support decisions around lending and other financial products.
Absa has pursued a related approach through Absa Next, which the bank introduced in October as a digital interface bringing together banking, payments, credit, savings, investments and business finance. The platform also allows people who are not existing Absa customers to access its services.
These developments illustrate how banks and fintech companies are competing to become more central to the financial lives of businesses and individuals. Payment processing remains an important entry point, but providers can pursue additional revenue and customer relationships through lending, savings and other services.
The opportunity is particularly relevant in a market where merchants already process substantial volumes of digital payments. Safaricom reported that its M-PESA merchant network had reached 3.13 million businesses, with transaction value of KSh41.68 trillion during its 2026 financial year. That network provides a large distribution base for services built around merchant payments and transaction histories.
SACCOs are also part of the expanding digital financial services market. TechTrendsKE reported that regulated SACCO assets reached KSh1.21 trillion in 2025, as these institutions expanded their use of digital credit, payments and member transaction data. Their position in the financial lives of members gives them a route into services that overlap with those offered by banks and fintech companies.
The expansion also brings payment providers into a more demanding regulatory environment. TechTrendsKE’s coverage of the proposed National Payment System Bill described provisions that would expand the Central Bank of Kenya’s supervisory powers, including inspection, intervention and consumer-protection responsibilities.
As fintech companies take on lending and other financial activities, their role in the financial system becomes broader. A platform that once handled payments may also influence access to credit, business cash flow and the management of customer information. That makes the quality of its financial services and the way it handles merchant data more consequential.
The next stage of competition will therefore involve how effectively providers combine payments with services that solve practical business problems. At Moonshot, executives pointed to cash-flow management, fraud prevention, customer insights and merchant support as areas where businesses need more assistance. Kenya’s newer merchant platforms show how those needs are being translated into products.
For African fintech companies, the commercial proposition is becoming broader: build a relationship through payments, then use that relationship to serve more of the business.
Go to TECHTRENDSKE.co.ke for more tech and business news from the African continent and across the world.
Follow us on WhatsApp, Telegram, Twitter, and Facebook, or subscribe to our weekly newsletter to ensure you don’t miss out on any future updates. Send tips to info@techtrendsmedia.co.ke