Kenya's digital lenders face tougher rules on AI, credit assessments and customer protection

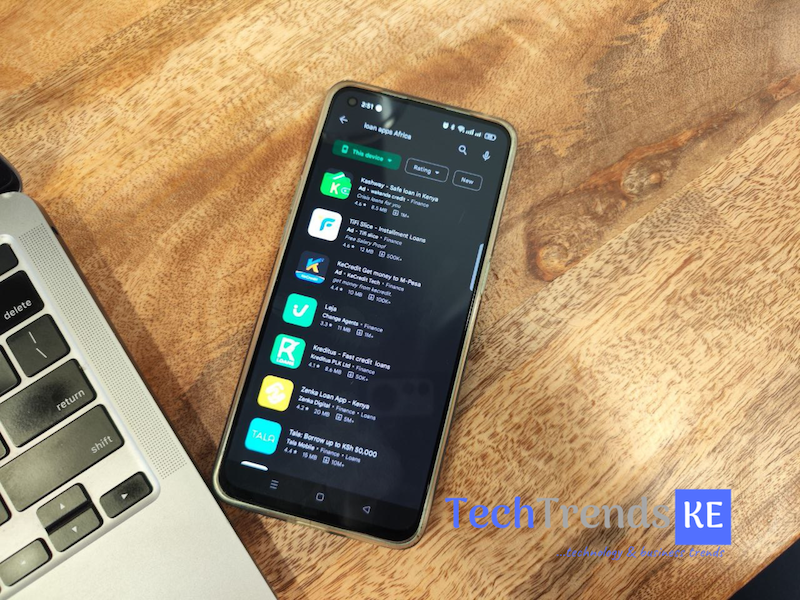
Kenya’s digital lending regulations now place specific obligations on providers using artificial intelligence to make credit decisions, requiring them to explain automated outcomes, disclose when customers are interacting with AI and maintain human oversight. The requirements form part of a wider framework introduced by the Central Bank of Kenya (CBK) for non-deposit-taking credit providers. They bring questions about how lenders assess borrowers, use personal data and determine credit limits into the country’s regulatory framework.
Regulation 60 of the Central Bank of Kenya (Non-Deposit Taking Credit Providers) Regulations, 2026, addresses the use of AI in lending. It requires providers to make automated decisions explainable to customers and inform them when AI is involved in an interaction. The regulation also sets expectations around human oversight, discriminatory bias, model accuracy, robustness, transparency and accountability. These provisions give the regulator a framework for examining how automated credit decisions are made and how providers take responsibility for them.
The regulations were gazetted on September 29, 2026, as Legal Notice No. 191 of 2026. They extend CBK oversight beyond digital credit providers to a wider category of non-deposit-taking credit providers, following amendments to the Central Bank of Kenya Act in 2024. The regulatory framework also introduces higher licensing and annual fees for providers, with application fees for licensed providers rising from KSh5,000 to KSh100,000 and annual fees increasing from KSh20,000 to KSh500,000. Registered providers face an annual fee of KSh250,000, while the regulations provide for a KSh1 million penalty for late payment.
The focus on automated decisions comes as lenders use more than conventional credit histories to determine who qualifies for a loan. Digital credit providers draw on transactional and communication data to develop credit scores, with mobile money histories helping them assess applicants who may have limited access to traditional forms of credit. This approach allows lenders to evaluate financial activity beyond the information available through conventional credit checks. It also places greater weight on the data providers collect and the models they use to interpret it.
Absa Bank Kenya’s Absa Next product, for example, offers instant personal and business loans ranging from KSh500,000 to KSh1 million using alternative credit scoring. Across the digital lending market, CBK says most loans remain below KSh20,000 and have repayment periods ranging from one week to two months. The regulator has described these facilities as sources of emergency funding and working capital, while noting that their size and duration limit their usefulness for investments that could materially improve borrowers’ earnings.
The scale of the market helps explain the regulatory attention. CBK reported that outstanding gross loans held by digital credit providers rose from KSh110.1 billion in December 2025 to KSh153.8 billion in June 2026. The number of loan accounts increased from 6.74 million to 8.9 million over the same period, while the average outstanding balance per account moved from KSh16,335 to KSh17,281. CBK had licensed 281 digital credit providers by September 2026.
The regulator has also proposed changes to how lenders review existing credit limits. Under the proposals, providers would stop automatically increasing customers’ limits and would conduct a fresh assessment of their financial circumstances before approving a review. That requirement addresses a feature of digital lending in which a customer’s previous borrowing and repayment activity can influence access to a larger facility. A new assessment would require lenders to consider the borrower’s current financial position rather than relying solely on an earlier lending decision.
Credit recovery presents another difficulty for providers. CBK has said the cost of recovering some loans can exceed the amount advanced, particularly where lenders are pursuing small balances. The regulator began licensing digital credit providers in 2022 after concerns about high interest rates and aggressive debt collection practices, including the public shaming of borrowers. The new framework places additional obligations on providers operating in a market where small, short-term loans can carry substantial recovery costs.
Borrowing across multiple providers also complicates the assessment of credit risk. Research by the Competition Authority of Kenya and Innovations for Poverty Action found that 33% of surveyed digital credit users had multiple active loans before the COVID-19 pandemic. Among people with loans from multiple providers, 52% cited emergencies as a reason for borrowing and 35% cited low loan limits. The research also found that borrowers taking multiple loans from different providers were more likely to default than those borrowing several times from a single provider.
FinAccess data provides another view of repayment difficulties. The 2024 Household Survey found that 16.6% of borrowers had defaulted without making any repayment, compared with 10.7% in 2021. The proportion who had paid late or missed a payment stood at 37.2%, down from 45.8%, while 45.9% reported no default, compared with 42.6% in 2021. These figures show different patterns of repayment performance across borrowers, while the findings on multiple lending point to the difficulty of assessing obligations spread across several providers.
For CBK, the regulatory challenge now includes how lenders use data and automated systems to make decisions, alongside the conduct of providers and the affordability of the credit they extend. The 2026 regulations set requirements for AI-driven decisions, while the proposed review of credit limits would place fresh financial assessments at the centre of lending decisions. As the market expands, the way providers calculate risk, explain decisions and evaluate a customer’s ability to repay will remain central to oversight.
Go to TECHTRENDSKE.co.ke for more tech and business news from the African continent and across the world.
Follow us on WhatsApp, Telegram, Twitter, and Facebook, or subscribe to our weekly newsletter to ensure you don’t miss out on any future updates. Send tips to info@techtrendsmedia.co.ke

