SBM Bank Kenya’s September results put its capital position and bad loans under scrutiny

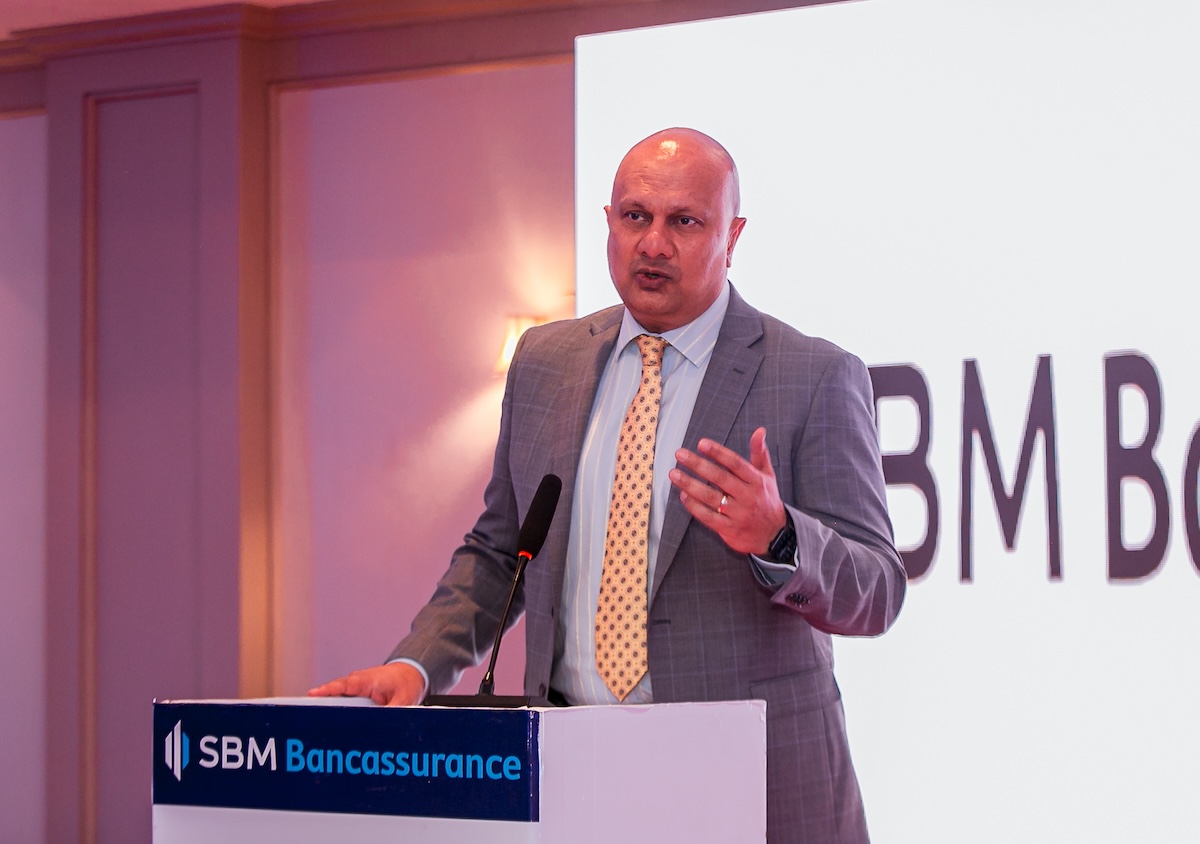
SBM Bank Kenya’s September 2026 financial results put its capital position and bad-loan exposure under scrutiny, following a strong earnings recovery in the first half of the year. The bank’s unaudited figures for the nine months ended 30 September show gross non-performing loans of KSh9.69 billion and a reported total capital-to-risk-weighted-assets ratio of 14.4%, just below the stated regulatory minimum of 14.5%. Its reported liquidity ratio, at 41%, was more than twice the statutory minimum of 20%.
The figures follow a first-half recovery in which SBM Bank Kenya reported pre-tax profit of KSh548 million, up 171.3% from KSh202 million in the corresponding period of 2025. Net profit after tax rose to KSh380.2 million, while the gross non-performing loan ratio fell to 17.3% from 32.4%. The September disclosures put the focus on whether the bank can sustain that recovery while managing credit risk and maintaining adequate capital.
SBM’s first-half recovery faces a third-quarter reckoning
The first-half results offered evidence of improving profitability and asset quality. Customer deposits rose 24% to KSh94 billion by June 2026, while net loans and advances increased 18% to KSh54.1 billion. The decline in the gross non-performing loan ratio was another important development for a lender working to strengthen its balance sheet.
The September figures now provide a further reference point for the bank’s performance. They report bank-level customer deposits of KSh75.62 billion, net loans and advances of KSh46.96 billion and total assets of KSh104.02 billion. The corresponding consolidated figures are higher, reflecting the distinction between the bank and its wider group, so comparisons with the June results need to use the same reporting basis.
The earnings figures also require careful reconciliation before the nine-month performance can be compared directly with the half-year result. The supplied September extraction reports bank-level pre-tax profit of KSh507.3 million, alongside group pre-tax profit of KSh547 million, but the operating income, expense and profit lines do not reconcile arithmetically. Establishing the correct figures is essential to determining how much of the first-half recovery carried into the third quarter.
Capital adequacy comes into focus
SBM Bank Kenya reported core capital of KSh8.39 billion and total capital of KSh8.43 billion at the end of September. Its core capital-to-risk-weighted-assets ratio stood at 14.3%, above the stated minimum of 10.5%, while the total capital ratio was 14.4%, marginally below the stated 14.5% requirement.
The core capital-to-deposit ratio was reported at 10.2%. Under the Central Bank of Kenya’s published statutory framework, the minimum core capital-to-deposit ratio is 8%, meaning the reported figure would be above that threshold. The total capital ratio, by contrast, is the measure that raises the immediate regulatory question, although the reported figures alone do not establish whether the bank has been subject to supervisory action.
Capital adequacy matters because banks need sufficient capital to absorb unexpected losses and support lending relative to the risks on their balance sheets. A narrow shortfall in a reported ratio does not, on its own, establish that a bank is in financial distress, but it warrants attention alongside the quality of its loans, earnings and funding.
The bank’s reported liquidity ratio of 41% provides a different perspective. It stands 21 percentage points above the stated minimum of 20%, indicating a stronger position on this particular measure than the reported total capital ratio. Liquidity and capital serve different purposes, however, and a strong liquidity ratio does not remove the need to maintain adequate regulatory capital.
Non-performing loans remain a major balance-sheet concern
Gross non-performing loans and advances stood at KSh9.69 billion in the September figures, against provisions of KSh2.74 billion. After provisions, net non-performing loans amounted to KSh6.95 billion. The bank also reported a discounted value of securities of KSh5.70 billion against those impaired loans.
These balances matter because problem loans can reduce interest income, increase provisioning costs and tie up capital that could otherwise support productive lending. Collateral can improve recovery prospects, but its value depends on enforceability, the time required to realise it and the costs involved. Provisions, meanwhile, provide an accounting buffer against expected credit losses rather than a guarantee that every impaired loan will be recovered.
The first-half results had shown a substantial improvement in the bank’s gross non-performing loan ratio, which fell to 17.3% from 32.4% a year earlier. That earlier progress makes asset quality a central measure to follow in assessing the September position. The gross loan book is needed to calculate a comparable September NPL ratio, while movements in provisions and recoveries would help establish whether the improvement was sustained.
Deposits, lending and the cost of expansion
SBM’s balance sheet shows customer deposits of KSh75.62 billion and net customer loans of KSh46.96 billion at bank level. The resulting net loan-to-deposit ratio is approximately 62.1%, although this calculation uses net loans rather than gross advances. Government securities worth KSh35.43 billion form another substantial part of the bank’s reported assets.
The composition of that balance sheet matters for a lender seeking to grow its customer base while managing credit risk. Deposits provide a major source of funding, while government securities can contribute interest income and liquidity, depending on their classification, maturity and availability. The bank’s reported KSh13.98 billion in balances due to the Central Bank of Kenya is also a significant liability that forms part of the wider funding picture.
SBM has continued to expand its physical presence, opening its 34th branch in Nanyuki in August. The expansion targets businesses across agribusiness, horticulture, tourism, conservancies and the small and medium-sized enterprise sector in the Mt Kenya region. The bank has also promoted digital banking through its Mfukoni platform and PesaLink transfers, broadening the ways customers can access and move money.
The financial question is how that expansion translates into sustainable returns. Branch growth can bring new deposits, borrowers and transaction activity, but it also carries staffing, premises and operating costs. Digital payments can generate additional customer activity and fee income, while better digital access may help reduce the cost of serving customers. The September results will be more informative once the income and expense figures are reconciled and the contribution of those activities can be assessed against the bank’s earnings.
For SBM Bank Kenya, the September reporting period brings together three issues that will shape its financial performance: sustaining the first-half recovery, containing credit losses and maintaining capital within regulatory requirements. The reported liquidity position provides a measure of reassurance, while the total capital ratio and outstanding impaired loans deserve close attention. The bank’s next set of comparable financial results will help establish whether the improvement seen in the first half has translated into a more durable recovery.
Real ESG impact doesn’t happen in panels alone, it happens in the rooms where financiers, operators, and policymakers actually align. Our GreenShift Forum 2026 cuts the noise, bringing together the people rewiring Africa’s sustainability and energy frameworks for one focused day in Nairobi. Secure your seat.
Go to TECHTRENDSKE.co.ke for more tech and business news from the African continent and across the world.
Follow us on WhatsApp, Telegram, Twitter, and Facebook, or subscribe to our weekly newsletter to ensure you don’t miss out on any future updates. Send tips to editorial@techtrendsmedia.co.ke