The business behind Kenya's food deliveries is expanding into groceries, subscriptions and customer loyalty
Kenya's delivery market is becoming a contest between platforms, retailers and restaurant groups


Simbisa Brands’ decision to take full ownership of its Kenyan delivery business points to a commercial contest that is becoming more complicated than the competition between food-ordering apps. Restaurant groups are investing in direct delivery operations even as Bolt Food and Glovo expand their merchant networks into groceries, household products and other retail categories. The Kenya food delivery market is developing along two competing models: businesses building their own distribution channels and technology platforms seeking to aggregate more of the country’s everyday spending.
Simbisa completed its acquisition of the remaining 25% stake in Kutuma Kenya for approximately KSh85.8 million, giving it full ownership of the delivery operation behind its Dial-A-Delivery service, according to reporting by TechTrendsKE. The transaction followed a period of growth for the business. Kutuma handled 3.23 million delivery orders in the financial year ended June 2026, a 59% increase on the previous year, the publication reported.
The acquisition gives Simbisa greater control over an operation that serves its restaurant brands, including Galito’s and other businesses in its portfolio. Kutuma has also indicated ambitions to develop beyond a dedicated restaurant delivery service and into a wider marketplace serving independent restaurants and other merchants.
That possibility puts the business in a different position from a conventional restaurant-owned ordering app. If Kutuma expands its merchant base, it will compete for orders with the same aggregators that restaurants use to reach customers beyond their own channels.
Restaurant groups are building their own delivery businesses
The economics behind restaurant-owned delivery are becoming more relevant as established food businesses seek closer relationships with customers.
Kuku Foods East Africa, which operates KFC in the region, has also discussed the role of its own ordering application alongside third-party delivery services. Kuku Foods CEO Jacques Theunissen said orders placed through KFC’s Uganda app were generating additional demand rather than simply replacing orders coming through Glovo.
That position suggests restaurants can use their own digital channels and aggregator partnerships for different purposes. A proprietary application gives a restaurant more direct access to customers and their ordering behaviour, while an aggregator offers access to a wider marketplace and an existing delivery network.
Simbisa’s acquisition gives that strategy a financial dimension. Full ownership of Kutuma allows the group to retain control over its delivery operation and make decisions about how the service develops. The marketplace ambition could also allow it to serve merchants beyond its own restaurant brands.
The model carries its own operating demands. A restaurant group running delivery infrastructure must manage technology, customer support, courier availability and fulfilment costs. It also needs enough order volume to support those expenses. Aggregators spread their technology and delivery infrastructure across multiple merchants, giving them a different cost structure.
The two models can therefore coexist, although their commercial interests may overlap when they compete for the same customer and transaction.
Aggregators are expanding beyond restaurant meals
Bolt Food’s expansion into supermarket and retail orders provides a clear example of how the marketplace model is developing.
In June 2026, Bolt Food partnered with Quickmart to bring more than 12,000 products from over 60 stores onto its platform, according to TechTrendsKE’s reporting. The selection included groceries, household goods, beverages and wellness products. The integration gave Bolt Food a retail offering that could serve customers with purchasing needs beyond prepared meals.
The partnership predates Ivy Maingi’s appointment as Bolt Food Kenya’s general manager in June 2026. In a November interview, Maingi said grocery and retail had grown to account for more than 20% of the platform’s business in Kenya, with the category recording triple-digit year-on-year growth.
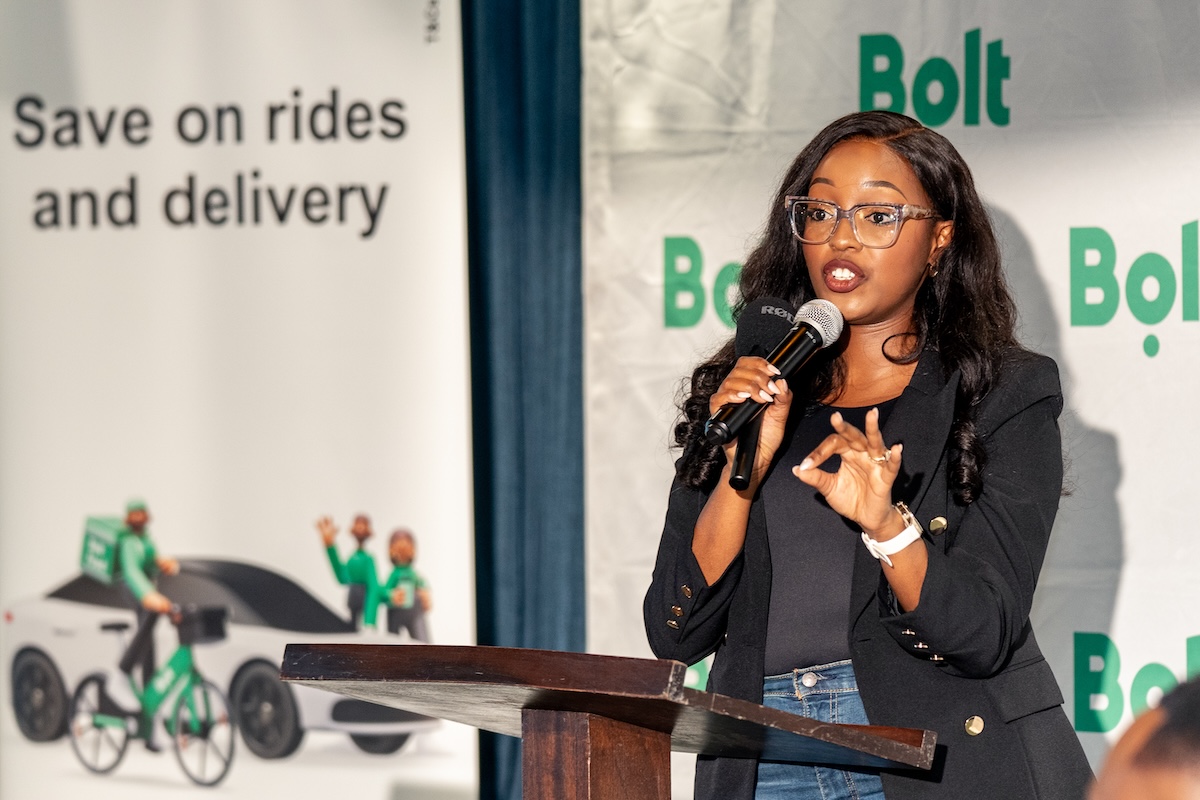
She also described an average ordering frequency of approximately four times a month across the platform. According to Maingi, grocery purchases are contributing to that frequency because customers can return to previous baskets and repeat routine orders. A household that orders takeaway at the weekend may also use the app during the week for items such as nappies, tissues and fresh produce.
The commercial implications extend beyond the delivery fee. A broader catalogue gives a platform more opportunities to engage customers, while repeat purchasing can help merchants reach consumers who may not otherwise visit their physical stores. It also gives retailers another route to serve customers who weigh delivery costs against the time and expense of travelling to a supermarket.
Glovo is pursuing a similar multi-category strategy. The company reported 40% order growth in Kenya over the previous year, with more than 6,000 merchants and over 2,200 active daily riders, according to TechTrendsKE. Glovo also said its platform had generated more than KSh20 billion in cumulative sales for merchant partners since entering Kenya in 2019.
Those figures provide an indication of the scale of its local marketplace, although they measure different aspects of the business from Bolt Food’s reported retail contribution. Glovo’s order growth cannot be directly compared with Bolt’s retail share, and its cumulative merchant sales are not equivalent to platform revenue.
The competitive direction is clearer than any direct ranking: delivery platforms are trying to make their applications useful across more purchasing occasions. Restaurant meals can attract a customer to the platform, while groceries and other products give that customer reasons to return during the week.
Retail orders are changing the economics of delivery
The expansion into retail creates opportunities for merchants and platforms, but it also changes what an effective delivery operation must handle.
Restaurant orders generally involve prepared products, defined menus and established kitchen processes. Grocery and supermarket orders can involve larger baskets, product substitutions, fresh produce and a wider range of picking requirements. The delivery platform must coordinate those processes while maintaining accurate order information and reasonable fulfilment times.
For retailers, the appeal lies partly in reaching customers through an existing digital marketplace. Quickmart’s integration with Bolt Food placed thousands of products within an application already used for transport and food delivery. Glovo’s merchant network offers a comparable route into online sales for businesses that may not have the resources to build and maintain their own ordering platforms.
The opportunity also extends to product discovery and advertising. Glovo has discussed retail media as part of its commercial strategy, using the platform to give brands and products greater visibility during the purchasing process. Its reporting on customer searches suggests that users frequently search by product category rather than a particular brand. That creates potential value for merchants and consumer brands seeking to influence what customers choose.
For the platforms, a larger catalogue can increase order frequency and create additional commercial relationships. But the value of that activity depends on fulfilment costs, merchant economics and customer retention. More orders do not automatically translate into stronger margins if each transaction requires expensive delivery or significant promotional spending.
Bolt Food’s subscription offering illustrates another way platforms are trying to influence purchasing behaviour. Bolt Plus costs KSh280 a month and provides free delivery on eligible orders from participating merchants, alongside benefits on eligible Bolt rides. Maingi described the subscription as a way to encourage customers to order more frequently.
Her explanation of the model included a contribution from participating merchants, which pay slightly more for Plus customers. The commercial proposition depends on whether additional order volume makes that higher merchant cost worthwhile.
The subscription also places more pressure on the platform to maintain a sufficiently broad network of participating businesses. Customers are unlikely to value a delivery membership if the merchants they regularly use are excluded or if the service cannot fulfil orders reliably.
Subscriptions add another layer to platform competition
Bolt Plus entered a market where Glovo Prime and Uber One had already introduced subscription-based benefits. The three products use membership to encourage more frequent engagement with their respective platforms, although their pricing and benefits differ.
For customers, subscriptions can make delivery costs more predictable. For platforms, they offer recurring income and a way to encourage repeat transactions. Merchants may benefit from additional orders, but the financial arrangement depends on the fees charged and the value of the customers attracted through the membership.
The model creates a commercial calculation that goes beyond the monthly subscription price. A customer paying KSh280 for Bolt Plus may place more orders because eligible deliveries no longer carry the usual delivery fee. Bolt must then balance the cost of those benefits against subscription income, merchant contributions and the additional volume generated.
The question for merchants is whether Plus customers spend enough to compensate for the higher participation cost. A rise in order frequency could improve sales, but the value depends on basket size, product margins and the cost of preparing and fulfilling each order.
That is particularly relevant for smaller restaurants and retailers, which may have less room to absorb platform charges than larger chains. Maingi has identified the merchant app, viable unit economics and responsive support as important factors in whether businesses remain on a delivery platform.
Courier networks will determine how far the market grows
The expansion of delivery categories also places greater demands on the people and infrastructure responsible for fulfilment.
Bolt’s separate parcel service, Bolt Send, passed one million deliveries in Kenya, according to TechTrendsKE. The company reported that order volumes increased by more than 135% between January and July 2026, with Nairobi accounting for over 95% of the orders. Bolt Send’s growth is evidence of activity in the company’s wider delivery operation, although parcel figures should not be treated as Bolt Food performance.
The two services operate in different segments, but they illustrate the potential value of a delivery network that can serve multiple types of demand. A courier network handling parcels and food may offer operational flexibility when demand varies across categories. That depends on how the platform manages availability, routing, service standards and the specific requirements of each order type.
Maingi has also said Bolt is encouraging couriers to use electric motorcycles through partnerships with electric vehicle providers. She estimated that electric bikes can reduce fuel costs by approximately 30% and said their maintenance costs are lower. She linked improved courier earnings to better retention and fewer service problems, although the fuel-saving figure and its operating assumptions were not independently established in the interview.
Courier regulation adds another responsibility to the operating model. TechTrendsKE has reported on the Communications Authority’s app-based courier licensing framework, which includes requirements concerning sender and recipient verification, parcel declarations, tracking and record retention. Those provisions are particularly relevant as platforms extend their services into general parcel delivery.
For food and retail platforms, reliable fulfilment remains central to customer retention. A broader product catalogue can bring more transactions onto an application, but late deliveries, missing items and inconsistent service can undermine the value of that convenience. The operational challenge grows as platforms handle different merchants, products and delivery requirements across more locations.
Kenya’s delivery businesses are therefore competing on several fronts. Simbisa is strengthening its ownership of a restaurant-linked delivery operation, while Bolt Food and Glovo are extending their marketplaces into more categories of retail. Subscriptions give platforms another way to encourage repeat orders, and courier networks remain essential to turning that demand into completed transactions.
The eventual balance between these models will depend on whether each can make delivery commercially sustainable for the businesses supplying the products, the people fulfilling the orders and the customers paying for the service.
Sign up for Bolt Business.
Go to TECHTRENDSKE.co.ke for more tech and business news from the African continent and across the world.
Follow us on WhatsApp, Telegram, Twitter, and Facebook, or subscribe to our weekly newsletter to ensure you don’t miss out on any future updates. Send tips to editorial@techtrendsmedia.co.ke

