Kenyan banks need to lend more to SMEs. Their digital platforms could help determine how

Kenyan banks are facing renewed calls to direct more financing towards small and medium-sized enterprises, raising an important question for the financial technology sector: can digital banking make it easier for lenders to understand and finance businesses that struggle to qualify for conventional loans?
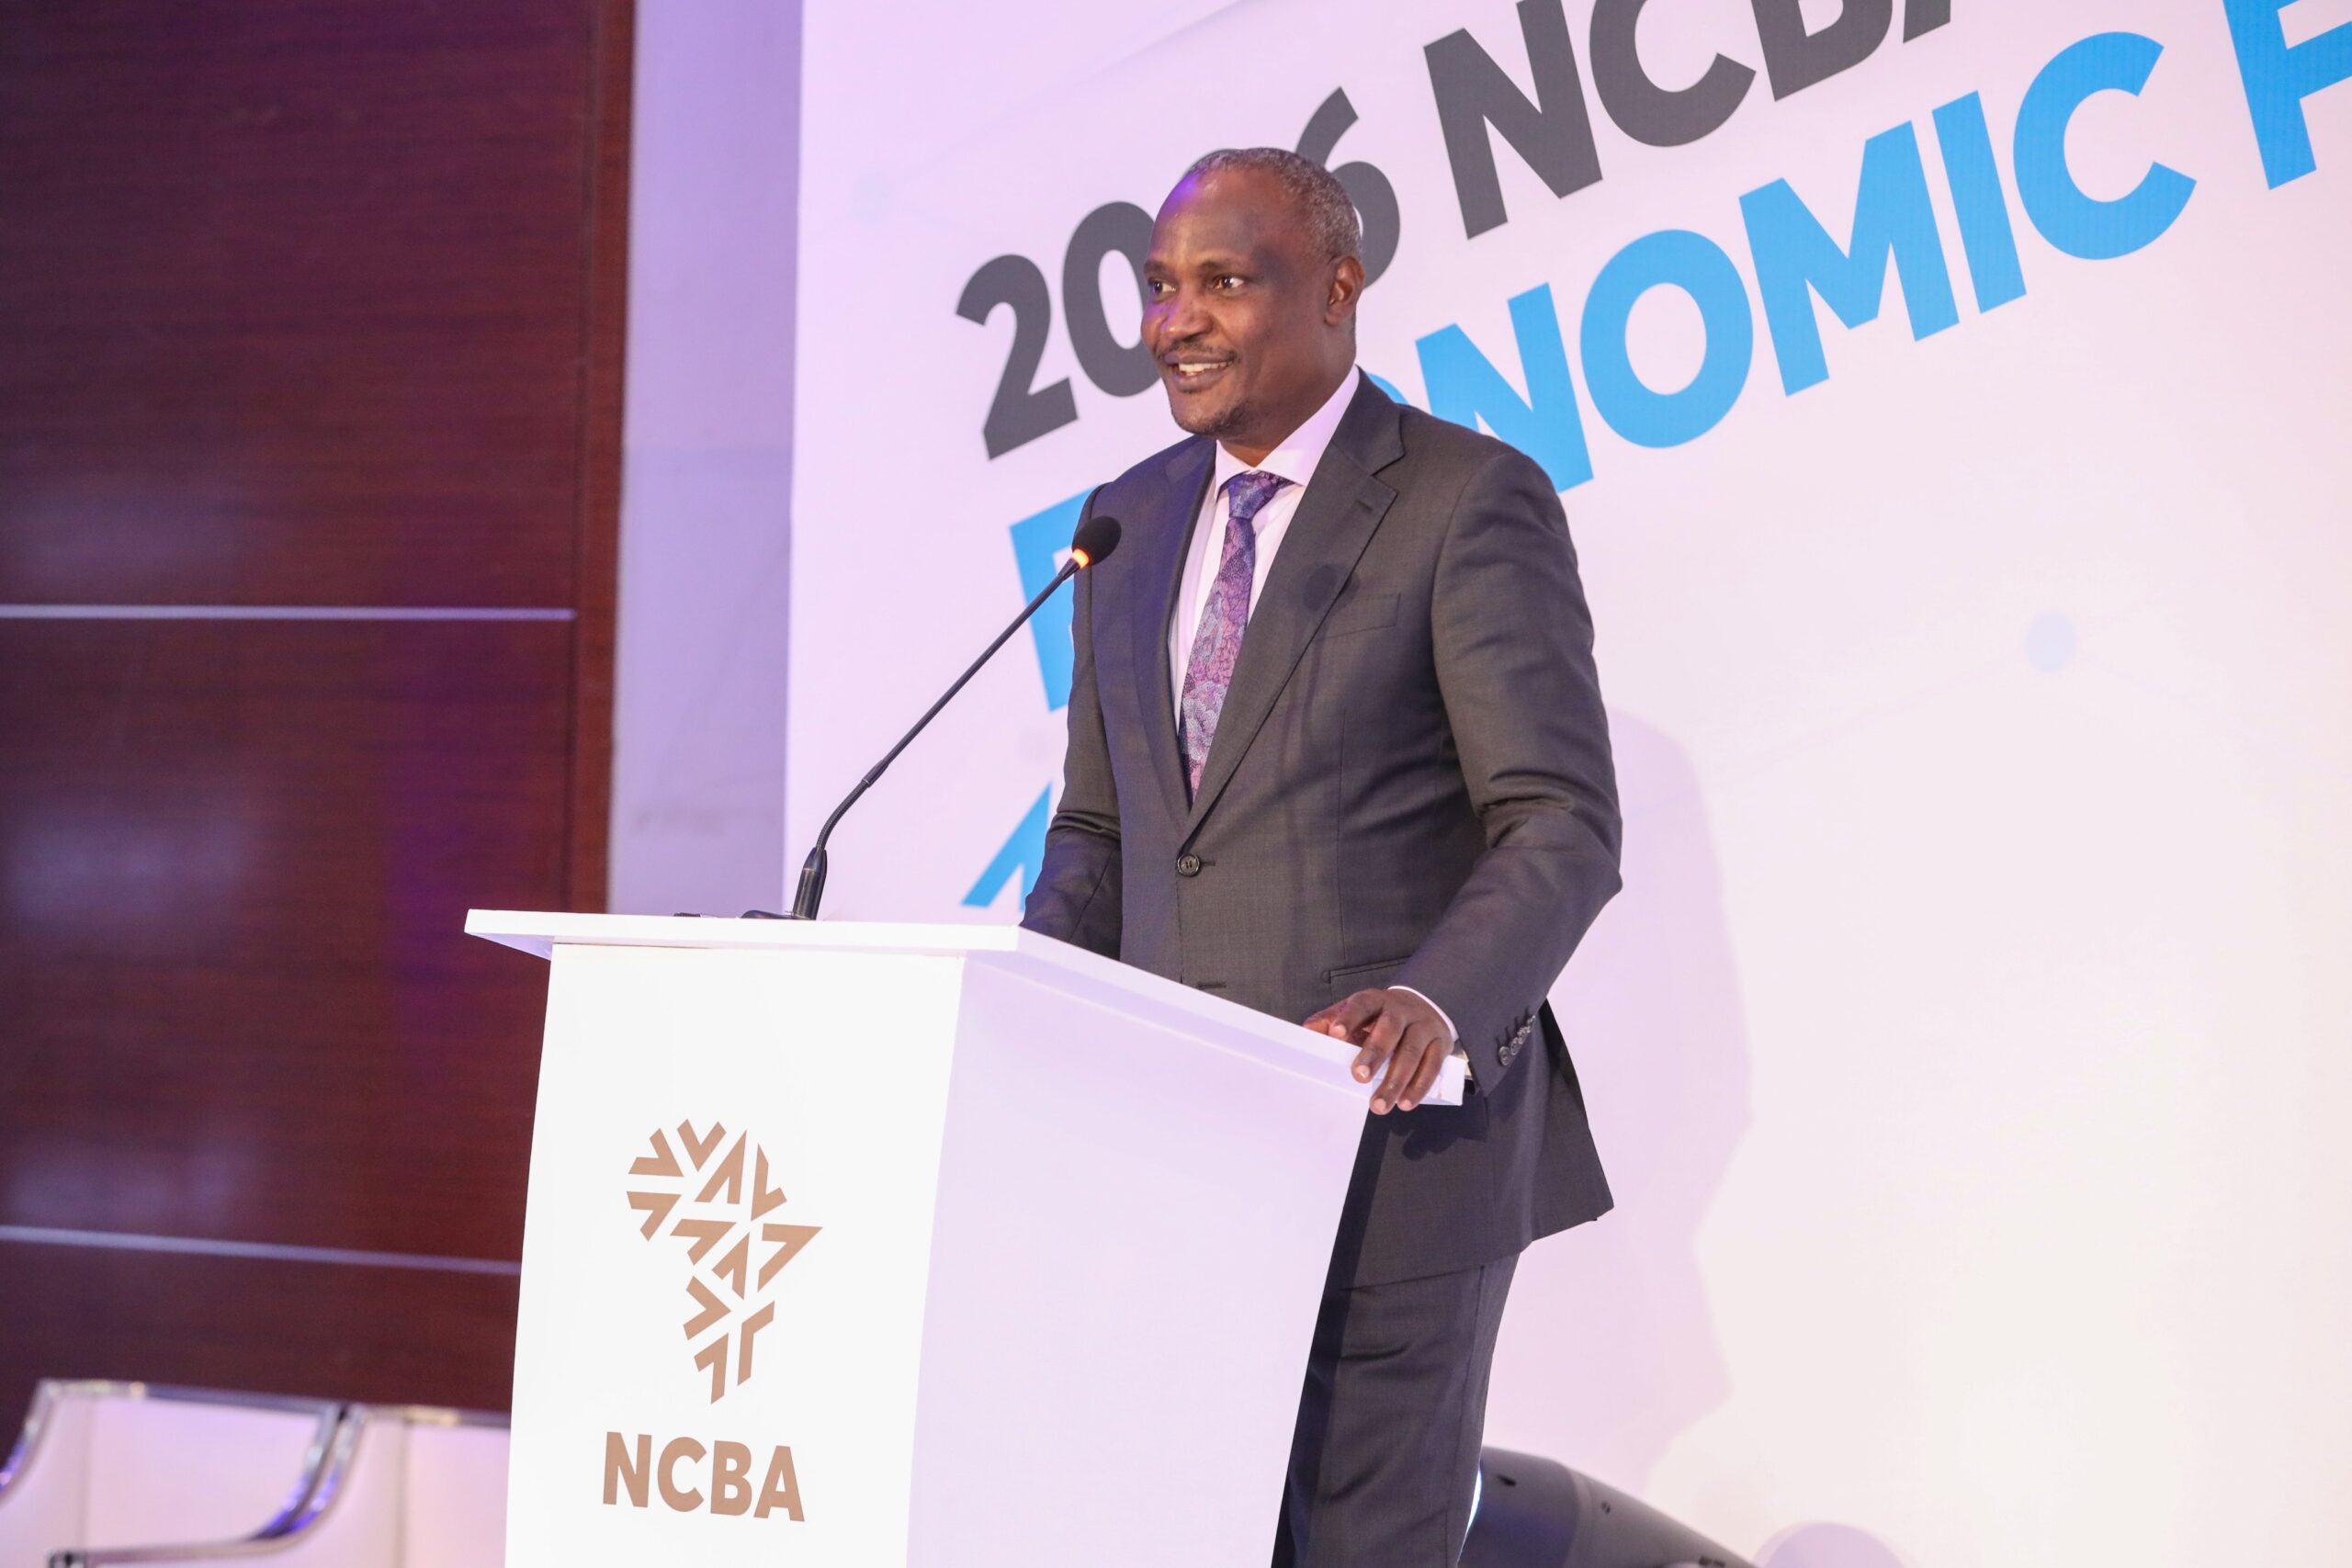
At the NCBA Economic Forum 2026, Treasury CS John Mbadi challenged banks to provide more financing to SMEs and support businesses in the productive economy. His remarks placed business lending within the wider discussion about private-sector investment, employment and the role of financial institutions in supporting economic activity.
For technology providers, the challenge extends beyond making loan applications available through mobile apps. Digital platforms can connect payments, sales records and other business activity, giving lenders additional information when assessing enterprises for credit.
Mbadi challenges banks to finance more SMEs
Smaller businesses need financing for everyday operations as well as expansion. A trader may need working capital to replenish stock, pay suppliers or meet operating expenses before receiving payment from customers.
Conventional lending processes can be difficult for businesses with limited collateral, inconsistent financial records or a short borrowing history. This creates an opportunity for financial institutions to use digital channels and business transaction information to develop more suitable lending products.
Mbadi’s call at the forum gives the banking sector a clear challenge: extend financing to more productive businesses and connect lending with the needs of the wider economy.
Merchant transactions create a new lending opportunity
Digital payments can provide lenders with a closer view of how businesses operate. Transaction records can show sales activity, payment frequency and patterns in the movement of money, offering information that may complement conventional financial statements.
This is particularly relevant to small merchants whose businesses generate regular transactions but may not maintain the kind of formal accounts traditionally required by lenders.
The use of merchant data in credit assessment can help financial institutions build a more detailed picture of business activity. It also creates an opportunity to connect financing with the actual performance of an enterprise rather than relying exclusively on conventional collateral requirements.
Digital platforms connect payments with business finance
Kenya’s financial services market is already moving towards platforms that combine merchant payments with other business services. NCBA’s LOOP BIZ+, for example, brings payment acceptance, working-capital loans, supplier credit, overdrafts and inventory management into one merchant platform.
The model connects financial services with the daily operations of a business. Payment activity can provide information about merchant performance, while integrated financial products give businesses access to services linked to their operational needs.
This approach places banks and fintech companies in a position to develop relationships with merchants beyond the processing of payments. It also creates opportunities to connect business finance with inventory, supplier payments and cash-flow management.
The challenge of turning transaction data into responsible credit
More digital transaction information does not automatically make every business eligible for a loan. Financial institutions still need to assess repayment capacity, manage credit risk and ensure that lending products reflect the circumstances of individual businesses.
The opportunity lies in combining transaction information with sound credit assessment and appropriate financing terms. For SMEs, that could mean credit products better aligned with sales patterns and working-capital requirements.
Mbadi’s remarks at the NCBA forum put greater responsibility on banks to support smaller businesses. Digital banking gives the sector additional tools to respond, particularly where merchant platforms can connect payments, business records and access to finance.
The challenge is turning those capabilities into lending that reaches more viable businesses and supports their ability to grow.
Go to TECHTRENDSKE.co.ke for more tech and business news from the African continent and across the world.
Follow us on WhatsApp, Telegram, Twitter, and Facebook, or subscribe to our weekly newsletter to ensure you don’t miss out on any future updates. Send tips to info@techtrendsmedia.co.ke

